Showing posts with label Cerner. Show all posts

Thursday, 15 February 2018

He Gone


To market to market to buy a fat pig. An hour before the US market opened, we had as one analyst put it "The most highly anticipated inflation number for the last 10-years". The expectation was for inflation of 1.7%; it came in at 1.8%. Confirming market fears, inflation is coming and so are interest rate hikes. Futures immediately dropped over 1%.

You will then be surprised to hear that yesterday was the fourth straight day of gains for US markets. Why the gain then? At the same time as the inflation number release, US retail sales came out; Retail Sales in U.S. Decline After December Revised Down. Huh? The biggest part of the US economy went backwards and stocks went up?

As you might have guessed, it has to do with interest rates again. Weak retail sales today, means that demand push inflation dissipates tomorrow, and the concern of increasing inflation is gone. So there you have it, bad data is 'good' data again. Until it isn't, but you will only find that out after the fact.

Market Scorecard. Our market spent the day in the green, until 15:30 when the US inflation data sent global markets crashing. Luckily with only minutes left of trading our market managed to squeak into the green again. The Dow was up 1.03, the S&P 500 was up 1.34%, the Nasdaq was up 1.86%, and the All-share was up 0.33%.


Company Corner

Michael's Musings

Last week one of our smaller holdings, Cerner released their FY numbers. They are the guys that are trying to remove all the paperwork you have to fill in every time you visit a medical professional. The goal is to create a network where you complete your information once, then from there, all doctors have access to it. Saving trees and saving you time. More importantly though, having the data in digital format, lowers the risk of bad handwriting leading to wrong diagnosis or the wrong procedure being done.

Built on to that is Cerner's management system, where hospitals can then use the information to easily see revenue and expense figures. It also allows them to see what operations are in the pipeline, meaning accurate forecasts can be made. Probably the most exciting part of the business is where they unleash AI onto the data. The clever algorithms take the data fed to it from all your medical tests, and at some stage in the future from your smartwatch too, and issue early warning signals around potential health issues.

Due to the time required and the capital-intensive nature of revamping a hospital group's computer systems, Cerner has a 'book' similar to that of construction company. For the 4Q, they had a record number of bookings, $2.3 billion, up 62% YoY. Over the last year, their revenue came in at $5.1 billion up 7% YoY. From that revenue they made a profit of $867 million.

Cerner ticks all the boxes, it is a technology company in the medical space. It is also defensive because once a hospital chooses Cerner, it is not easy to move to a competitor. Thanks to those characteristics, it trades on an 'expensive' 24 times earnings. Management expects earnings to grow by 11% over the next year so the multiple isn't going to unwind in a hurry. With many things in life, you get what you pay for. Paying up for Cerner is one of those things in our opinion.


Byron's Beats

When Aspen released their full year results last year, the second half of the year was much better than the first half. Stephen Saad, at the results, mentioned that he expected this momentum to continue into the financial year 2018.

This morning we received a trading update which indicated as such. Here are the numbers.
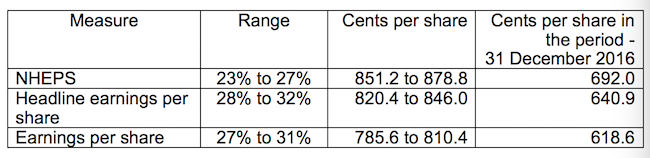


This is all the info we have access to but let's delve a little deeper into each 6 month number over the last 18 months. To be consistent let's look at the normalised headline earnings per share (NHEPS). Last year this time the company made 692c for 6 months. For the full year they made 1463c which means they made 771c in the second half. This trading update suggests they have made 860c (middle ground) which shows an 11.5% improvement on the second half of last year.

The first half of last year was off a low base but the growth off a very solid second half base still looks strong. The market has reacted very positively to the news, the share is up 6%. The detailed numbers will come out on the 8th of March, more details then.


Linkfest, lap it up

One thing, from Paul

Finally, Zuma is gone! Under his leadership South Africa slipped very badly. He says that he doesn't know what he did wrong? Well, apart from anything else, the country faces a dire fiscal crisis, thanks to his bungling.

His involvement in the gross mismanagement of public enterprises is well known, and the debts of a looted and bankrupt Eskom will doubtless be added soon to the sovereign debt mountain.

The ANC leadership crisis had already derailed the State of the Nation Address, and the postponement of the Budget Speech was next.

The Moody's Baa3 rating is the only thing keeping our bonds debt in the Citi World Government Bond Index, given that the grades from S&P Global Ratings and Fitch Ratings are already below investment grade.

The rules of the index require that a borrower can no longer be included once it's rated junk by all three rating companies. Moody's deadline is 23 February. They are probably waiting to see if the Government has the guts to do what must be done: raise the VAT rate from 14% to 16%.


Bright's Banter

My favourite academic Prof. Scott Galloway has been singing this song of breaking up big tech i.e. Apple, Amazon, Google/Alphabet, Facebook and Microsoft. Here's his reasoning on why we should build em and break em up!

Bust Big Tech Silicon Valley

Apple's smart speaker, the HomePod is now available for purchase, the sales went live this past Friday and the reviews are flying in! Apparently its a great quality speaker but is not in the same league as the competition when it comes to being "smart".

I think the problem is not the speaker, but Siri. Siri's had the first mover advantage but never really grew from there. On the other hand Alexa just lapped Siri on her amazing ability to learn.

The graph below shows how these speakers (Google, Amazon Echo, HomePod etc.) perform head to head.

Infographic: Apple's HomePod Is Not as Smart as Its Rivals | Statista You will find more infographics at Statista


Home again, home again, jiggety-jog. The Rand is stronger this morning, trading at $/R11.68. No, not because we no longer have a president but because of the US inflation data. We know who our future president will be, the question that the market will be asking is who will be delivering the budget speech next week Wednesday? With the Chinese New Year, Chinese markets are closed today and tomorrow, and Hong Kong had a half day of trading today. After a busy news data day yesterday, there is nothing major out today.


Sent to you by Team Vestact.

Email us

Follow Michael, Byron, Bright and Paul on Twitter

078 533 1063

Tuesday, 7 November 2017

Apple in Paradise


To market to market to buy a fat pig. The Paradise Papers will be a talking point for the coming weeks as more details emerge. The latest big name revealed is Apple, who went 'tax haven shopping' after their setup in Ireland ran into issues - (Apple had five burning questions about the best tax haven for its billions). These multinational companies spend millions to ensure that they are structuring their tax affairs legally. The problem is that tax codes can be open to interpretation, as seen with Apple and Ireland. The EU feels that Apple pushed things too far and should pay Ireland $13 billion, Ireland is appealing the decision. When a country doesn't want $13 billion in tax revenues, you know how subjective tax codes can be.

As I said on CNBC yesterday, it is management's job to pay as little tax as possible legally, and it is government's job to decide what the tax codes should be. The problem for governments at the moment is the ambiguity in the way tax codes and treaties that have been drawn up. Loop holes are being closed and standardisation of definitions are being implemented. We have also seen that large financial institutions have had pressure put on them not to do business with entities linked to tax havens. If you want to read further about the initial names linked to the papers, here is a brief summary - Here's a guide to the major revelations in the Paradise Papers. What is interesting to me is how many of the 'big guns' are intertwined in many business deals.

Market Scorecard. Our market powered through the 60 000 mark yesterday on the open, meaning it has taken just under 3-years to climb 20% from 50 000 points to 60 000. The Dow was up 0.04%, the S&P 500 was up 0.13%, the Nasdaq was up 0.33% and the All-share was up 0.57%/. Lonmin was down another 5.9% yesterday, but after being one of the best-performing stocks for October it is still trading higher than it was in September.


Company corner

Byron's Beats

Last week we received third-quarter numbers from Cerner which disappointed the market. The share dropped 9% on the news as forward guidance was revised down. We should put that drop into perspective. Even after that fall, the share price is up 38% so far this year. It all depends on where you draw the line in the sand. Having said that, this has been a volatile ride. This business is a high margin software company with high expectations. A volatile ride usually comes with that package.

Bookings for the quarter came in at $1.1bn. This was much lower than expectations because a few large contracts will now only be included in the fourth quarter numbers. When these bookings reflect, it should result in an all-time high bookings for the full year. It has been a good year with some big government institutions signing up for their healthcare software services.

Revenues came in at $1.276bn which was 8% higher than the comparative quarter; $928 million of that came from support, maintenance and services. You can see that this is a retention business. Once you have signed up a hospital or an institution, their annuity business is a key driver of Cerner's future profits.

Another important factor to note is that only $142 million of these revenues came from outside the US. The potential to expand globally is massive.

Earnings for the year are expected to come in at around $2.42 per share, putting the company at 27 times forward earnings. The business does have gross margins of 83% and very impressive cash flows which explains the high multiple somewhat.

We remain buy rated on this stock as it continues to secure solid government contracts in the US. We will do a more detailed analysis of the full year when those numbers come out next quarter.


Linkfest, lap it up

One thing, from Paul

The biggest aggregate client position in our New York business is Apple. Not surprising really, because it is a must-own stock and has done really well in recent months. The total value of our Apple holding at Fidelity Clearing & Custody Solutions (where the shares are held in safe custody) is $15.1 million.

At its current share price of $174.25, Apple has a market value of just a whisker over $900 billion. That makes it the most valuable listed company in the world. It is the first time that any listed company has breached that mark. Well done Tim Cook. Onwards to $1 trillion!

The reason that the stock is trading so well is that this coming holiday season will probably be the biggest ever, as shoppers go mad for its new iPhone X. Those have the new larger OLED screens and cost over $1,000 each. They are selling out as they hit the stores, but Apple's formidable production system will soon have them available for sale around the world.

This article provides some updates on the opening iPhone X weekend - Apple iPhone X draws lines, and some activation errors on AT&T and Verizon services


Michael's Musings

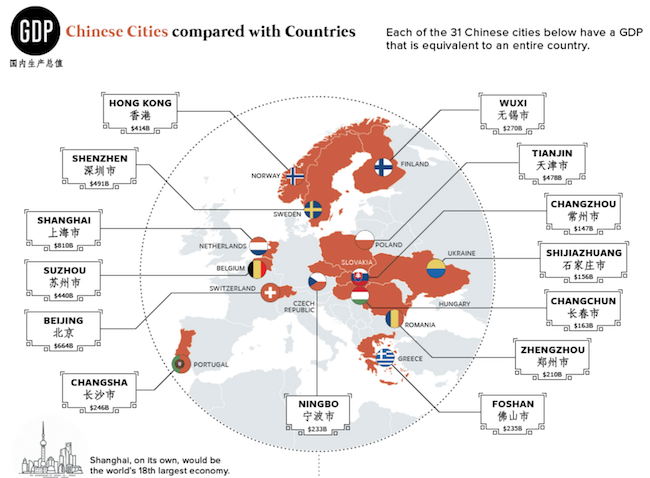
We sometimes forget how massive China really is. The following graphic shows how China's biggest 31 cities are a similar size to certain countries - 31 Chinese Cities With Economies as Big as Countries.


A question that is as important as when to buy is when to sell. Given that we are not market timers, and don't try jump in and out of the market, we look to sell when something has fundamentally changed at the company - The Question of When to Sell Isn't So Simple. The last point that Barry makes is important, even a well-timed sell and then corresponding buy can be break-even at best due to taxes and transaction costs. How much does a stock need to drop before your losses would be more than the taxes and costs incurred in selling?


Bright's Banter

One of my favourite quotes from Howard Marks taken straight from his book The Most Important Thing

    "When people say flatly, 'we only buy A' or 'A is a superior asset class,' that sounds a lot like 'we'd buy A at any price; and we'd buy it before B, C or D at any price.' That just has to be a mistake. No asset class or investment has the birthright of a high return. It's only attractive if it's priced right.

    Hopefully, if I offered to sell you my car, you'd ask the price before saying yes or no. Deciding on an investment without carefully considering the fairness of its price is just as silly. But when people decide without disciplined consideration of valuation that they want to own something, as they did with tech stocks in the late 1990s---or that they simply won't own something, as they did with junk bonds in the 1970s and early 1980s---that's just what they're doing.

    Bottom line: there's no such thing as a good or bad idea regardless of price!"


In the following article, Howard Marks explains why passive investing is not the silver bullet you have been looking for! - Howard Marks On Passive Investing


Home again, home again, jiggety-jog. Tencent is up over 3% in Hong Kong, expect a raging Naspers when the bell goes at 9:00 our time! There is CPI data out of the EU around lunch time and then this afternoon, the JOLTs number from the US. As the US reaches full employment, the JOLTs data becomes more important.


Sent to you by Team Vestact.

Email us

Follow Michael, Byron, Bright and Paul on Twitter

078 533 1063
Wednesday, 2 August 2017

Cerner's Healthy Margins

To market to market to buy a fat pig. Another green day for both our market and the US market, the S&P 500 was up 0.24% to just short of an all time high. Thanks to the strong surge in the Apple share price after hours, the S&P 500 is set to open at a record high today. Good times.

An interesting rule change from the S&P on which companies will be allowed into the index in the future (The S&P 500 is making a new rule). The rule will exclude new companies being included that have multiple share classes, with the first casualty being Snap Inc. Does this mean going forward that the S&P will start removing companies already in the index who have multiple share classes? Big hitting companies who have multiple share classes includes Alphabet (Google), Berkshire and Under Armour. Imagine saying that you want to buy the US market but the EFT you buy doesn't include the first 2 companies?

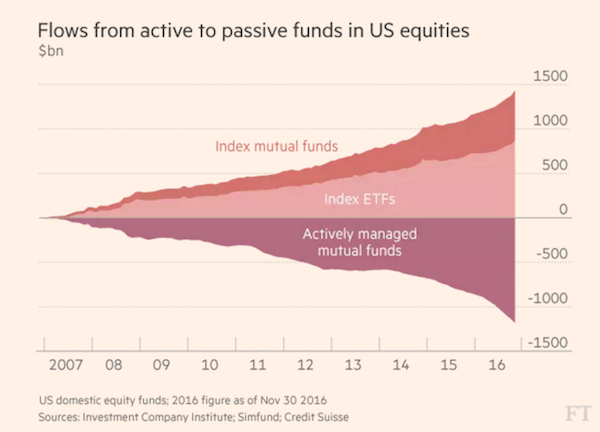
With the big move towards index trackers, the rules determining the index start to hold more significance (ETFs are eating the US stock market).


Companies that don't make the cut will most likely trade on lower multiples as their shares are left dry from the flood of index tracking ETFs. Distortions like this creates opportunities for more active investors, which is good news for you and I. The growing passive space should result in more room to move for active investors because a passive investor buys a company due to it being in an index and for no other reason. So an over-bought stock could be bought up more, creating the opportunity for active investors to short the stock. Or as we have spoken about, some companies may be left out in the cold even though they are cheap and a great buying opportunity.


Company corner

Byron's Beats

The third quarter is usually the most boring in Apple's cycle. That is because it is the quarter before new product releases are announced which also coincides with the festive season. Not much was expected of last night's results. I must say, I was expecting a disappointment because I personally know a few people who are holding out on renewing their contracts until the new Apple phone is released, hopefully in September.

But that was not the case and the results smashed expectations, pushing the share up 6% pre market. Quarterly revenue came in at $45bn compared to $42.4bn this time last year. The company's cash balance now sits at a whopping $261.5bn. Just Wow!

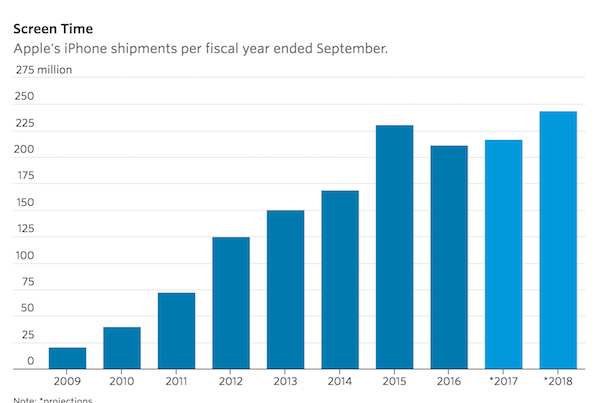
Profits for this quarter came in at $8.72bn, up 12%. Guidance for the next quarter indicated some exciting product launches. See the image below from Wall Street Journal which shows the magnificent rise of the greatest product of all time. More records are expected in 2018.


Pleasant surprises included a rise in the iPad business for the first time in 4 quarters. Mac sales rose 6.7%, the third quarter of gains in a declining notebook market. Services grew 22% to $7.27bn as it becomes more and more significant. Lets hope for more exciting content coming to iTunes subscribers.

Apple continues to be one of our favoured stocks in New York. For a company of this quality, trading at 17.5 times earnings, we think it is a no brainer. Expect more news from these guys soon when those product releases come out.


Michael's Musings

Last week Cerner released their 2Q numbers which were largely inline with what the market was expecting. Revenues were up 6% to $1.29 bn, with the more important numbers of Bookings, up 16% to an all time high of $1.64 bn. Revenue Backlog was up 11% to $16.65bn. On the profit side of things, Adjusted Net Income was up 3% to $206 million, which translated into EPS of $0.61, 5% higher (thank you share repurchase program).

Two noteworthy new customers signed up during the last quarter were, LifePoint Health and the Department of Veterans. LifePoint Health operate 72 hospitals, the rollout is only in a handful of their hospitals for now but in time you would imagine all the hospitals will be running on Cerner systems. For the Department of Veterans, they were elected as lead in "next-generation electronic health record system". Things are still in the planning phase and contracts are still being signed. Of significance though is Cerner beating out the competition to be chosen by a large government department.

Going forward the company gave guidance that their Full Year(FY) Revenue should be around 8% higher and that FY EPS should be around 6% - 11% higher, meaning that the current P/E ratio of 32 isn't cheap. The market gives Cerner this premium due to the long term steady growth potential from the company, where they have a very healthy operating margin of 19.3%. Also, only 10% of their revenues comes from outside of the US, once they are done conquering the US the rest of the globe will be ready for the taking.


Linkfest, lap it up

A note from Paul

Bitcoin is splitting in two? What does this even mean? Too complicated. I'm out! (Bitcoin splits in 2)

Tesla batteries to be used by power utilities? This could be big! (Tesla Batteries May Back Up Wind Farm Off Massachusetts Coast)


Bright's Banter

Failed In Loans Trying High Yield (FILTHY) - A perfect example of pro-risk behaviour by Pension Fund Investors in Europe where FOMO and the low interest rate environment forces these investors to over reach for returns without any risk consideration (European loan fund boom sparks concerns over risk taking)


Home again, home again, jiggety-jog. Numbers to be on the look out for later today are, the ADP Nonfarm Employment change and then probably more significant to us in South Africa, the Crude Oil Inventory number from the US. The change in inventory will give an indication of what the demand picture looks like in the US, having a knock on effect on the oil price which has found a new home above the $50 a barrel mark.


Sent to you by Michael, Byron and Paul on behalf of team Vestact.

Email us

Follow Michael, Byron, Bright and Paul on Twitter

078 533 1063
Monday, 10 July 2017

EV growth is Electric

"Now that the battery is a whole lot more affordable than at any time in history, it makes more economic sense to power your vehicle from home and then heigh ho, off you go. The thing is, in countries that still burn a lot of coal to generate electricity, are you really doing the climate a favour by plugging into the grid?"


To market to market to buy a fat pig Stocks Friday in Jozi gave up ground across the board, all the major indices were lower on the day. Again, some of the new 12 month lows were reflective as to what has been going on in the economy, the likes of Woolworths, Life Healthcare and Spur are all trading at year lows. Astoria reported a Dollar NAV that clearly surprised to the upside, the stock is now at a 12 month high. Astoria of course is a listed holding vehicle/fund for US stocks, based out of Mauritius, priced in Rands here in Joburg. All the assets however are foreign, making the vehicle attractive at some level. This morning we have started on a better and more even keel, the currency has juiced up a bit.


It was jobs Friday. That was, the Friday last, where the multiple talking heads thrash out why this jobs number is so important and more important than the last one. Of course, as is often the case and I try and test this theory, nobody remembers the numbers from two months ago. The number from the Bureau of Labor Statistics is often prone to revision. The full report is always called, The Employment Situation - June 2017. A strong jobs report at face value makes for a mixed Fed, darn that job is tough!

Stocks in New York, New York, most especially technology stocks, rallied sharply. The nerds of NASDAQ rallied over a percent by the close, the broader market S&P 500 gained just shy of two-thirds of a percent, whilst the Dow Industrials, weighed on a little by energy stocks (down 0.15 percent as a collective), managed to add just over four-tenths of a percent. Facebook added one and three-quarters of a percent, the stock is still around two odd percent from the all time highs, so much for the great technology sell off of 2017. I shouldn't be so smug, it may well come!

In sad news over the weekend for one of the companies that we recommend, one of the founders and CEO passed away - Neal Patterson, Cerner's Billionaire Co-Founder CEO, Dies at 67. It is sad, a reminder that we all have a finite amount of time. One can look back at the legacy that the man left, it is pretty amazing that he achieved this much and built something of this magnitude. I am sure that all and sundry will miss him.


Wow. The rate of adoption is just astonishing. And whilst we all believed that this would happen, the evolution of the Electric Vehicle (EV), I suspect that it has happened quicker than most people would think. There are some countries that are committed to eliminating fossil fuel powered vehicles by certain dates. I suspect that it is just a cost thing. If a consumer is presented with two vehicles, exactly the same, one is an electric one with fewer moving parts, one is the combustion engine, and more importantly they cost the same, which one do they choose? There is the important point about the outlay of a charging station at home (the installation cost) and wondering about moving through the countryside trying to find a charging station reliably.

There is a great report free from Bloomberg (you just have to enter a few details) - Electric Vehicle Outlook 2017. There is another Bloomberg article, from earlier last week titled The Electric Car Revolution Is Accelerating, with this important price per unit (for the battery):


Now that the battery is a whole lot more affordable than at any time in history, it makes more economic sense to power your vehicle from home and then heigh ho, off you go. The thing is, in countries that still burn a lot of coal to generate electricity, are you really doing the climate a favour by plugging into the grid? No. You have to spend a whole lot more money in getting the rooftop network and batteries installed. Of course, as this FT article (subscription only) points out, Electric car growth sparks environmental concerns. The inputs still need to be mined, as well as recycled. I suspect that in a modern world we are more equipped to deal with these matters.

As ever it is about the economics. Is the price affordable. At the same time, talking affordable cars, the fellow who changed all of it was Elon Musk. He took delivery of the first Model 3 - Tesla Rolls Out Its First Model 3, and It's Elon's. At least Musk agrees with Henry Ford, who famously said about the Model T: "Any customer can have a car painted any color that he wants so long as it is black." There is a shortened version that is known well. Here goes, one of the first photos of the electric vehicle that may well be the vehicle that pushes more people to other models. i.e. If you want a Tesla, and cannot afford it (even the 35 K USD one), then many other manufacturers are making more affordable vehicles.


The question arrises, who wins and who loses in this scenario? The manufacturers can refit factories to build battery vehicles, humans still need transportation. Car sharing and car pooling with autonomous fleets? Does that mean lower overall demand? What does that mean for the roads, the filling stations, automobile mechanics, the big oil businesses, the countries reliant on oil production to balance their budgets. As with the industrial revolution, there is a re-skilling of people across the globe, they find their jobs elsewhere and don't just starve and wander around like zombies. It does feel like a shakeup is coming, courtesy Artificial Intelligence, Autonomous Driving/Fleets and Battery Operated vehicles, the future is here friends.


Linkfest, lap it up!

Here is the annual list from BI of who to follow on Twitter, just after heavy weight Cullen Roche you will find Paul's name - The 125 most important finance people you have to follow on Twitter.

Thanks to the likes of Instagram, traveling is high on the priority list of millennials. Which passport works the best for traveling? (What is the World's Most Powerful Passport?). Sasha points out that African countries should consider dropping their Visa's to high tourist nations like Germany.


If you want to eat what ever you want, cycle the Tour de France - A Tour de France cyclist burns 6,071 calories a day - here's how many Chipotle burritos that is. Two things stood out to me, firstly the massive amount of energy needed to complete a stage but also how high the calorie count is in junk food. No wonder obesity is on the rise, it is so easy to get more than your recommended calorie count in just one meal.


Home again, home again, jiggety-jog. It is the start of earnings season. Which is simply great. The real business of business, the real down and dirty of the job. The coal face. The cricket? I don't want to talk about it, ok?


Sent to you by Sasha, Byron and Michael on behalf of team Vestact.

Email us

Follow Sasha, Michael, Byron, Bright and Paul on Twitter

078 533 1063
Friday, 5 May 2017

Cloudy on Healthcare

"That certainly looks like a good company to own, one with rising revenues and earnings, right? Yet unfortunately we are hard wired to see that the price of a stock and link that to a company's "well-being". That is unfortunately the wrong way to go about investing. In large part we have resisted the selling of what is a good business. We will hold it through the (perhaps) Obamacare repeal, which now needs to go through the Senate - Senators Set to Write Their Own Version of the GOP Health Bill."


To market to market to buy a fat pig Markets locally were lower to mixed here in Jozi, Jozi, stocks at the end gave up around one-third of a percent by the close. Industrials were marginally higher, resource stocks were taking pain from commodity prices that have definitely been sold off. Part concerns over the supply side being still too strong and the demand side being average. In other words, for iron ore markets it may be as simple as strong Australian supply may be more than meeting tepid Chinese growth. I think in the end all of these factors will be fine and meet their balance, commodity price markets tend to be very volatile and as such it is a sector of the market that we do not view favourably for retail investors.

The stocks that took some pain were the likes of FirstRand, MTN, AngloGold Ashanti and Anglo American. AB InBev was on the top of the leaderboard with a quarterly update that was well received by the market. The brewer rose nearly 7 percent on the day, Richemont has continued to see follow through (like all the luxury stocks), up at 116 Rand a share and at the best levels in 18 months. And in fact near an all time high. As is Naspers. So what has transpired over the last few months is that the rally in the equities market (relative) has been led by industrials (the return of AB InBev has helped too). At the expense of the mining shares.


Stocks over the oceans and far away made a fist of things from the worst part of the session around midday, in the end stocks were flat to marginally higher. The Dow ended the session down a smidgen, both the S&P 500 and the nerds of NASDAQ were just a little higher. Eddy, in his newsletter this Friday pointed out that volatility was exceptionally low and that the range for the S&P over a few sessions was almost zip. Zero, nil. Niks. No range of any sort. Volatility story - The Mystery of the Stubbornly - Low Volatility Index Is Deepening.

Facebook closed the session down around two-thirds of a percent, there was a whole host of broker upgrades after these numbers. There really are endless opportunities for this business, they are going to make sure that they stay on top of their advertisers and more importantly their community. They are definitely going to continue to change the world. To think that the estimates are for 50 billion Dollars of revenues this year, they have around 32 billion Dollars worth of cash and that same business did not exist 15 years ago. A time when people were still licking their wounds from the dot-com crisis. Non-farm payrolls today. That will have an impact on markets.


Company corner

Cerner, the IT healthcare services business, reported numbers for the first quarter last week. Quarterly revenues rose 11 percent when compared to Q1 2016, it was at the top end of guidance given by the company. Earnings per share clocked 52 US cents, compared to 43 cents this time last year. Guidance for the coming quarter was at the top end of the range around 1.335 billion Dollars, with earnings per share likely to be in the region of 61 cents per share. For the full year, the company expects the mid point of the range to be 2.5 Dollars of earnings.

That means at the current share price of 64.28 Dollars a share, the stock trades forward at around 25 times earnings, relative to the growth prospects it looks a bit rich. The share price has been all over the show, at the depths of despair in December last year through to January this year. Since then however, the share price has been on an absolute tear, year to date the stock is up 35.7 percent. We like the space and the sector, the share price had reached an all time high of 75 Dollars a share back in April of 2015, around two years back.

Cerner has four decades worth of healthcare and information technology integration experience. They are one of the first to digitise medical healthcare records. The cofounders are very much still at the helm of the business, both Neal Patterson and Clifford Illig are in the Chair/CEO and Deputy-Chair roles respectively. Their solutions are smart, from devices connected, to feeding their cloud databases, to billing systems, to better help the business of hospitals, to focus on the important roles in providing quality healthcare.

Healthcare and hospitalisation is an emotive and complex affair, no two humans are the same, neither is their care. What the patients, the caregivers and the broader role players all want is continuity and world class care. Through advanced and specialised tools, time is saved and better care is given. Simply put, this business has loads of room to grow. They really do. The older and more technologically integrated the whole world gets, the more data there will be to put together for all our health records.

Revenues have seen astronomical growth, since the business went public in 1986 they have compounded by 21 percent per annum. And judging from their order books, there still is a lot of work to do. Retire paper and keep a data trail. This will help everyone. Not only will this business continue to steadily grow revenues and profits, it fulfils the role of being a humanity improving investment too.

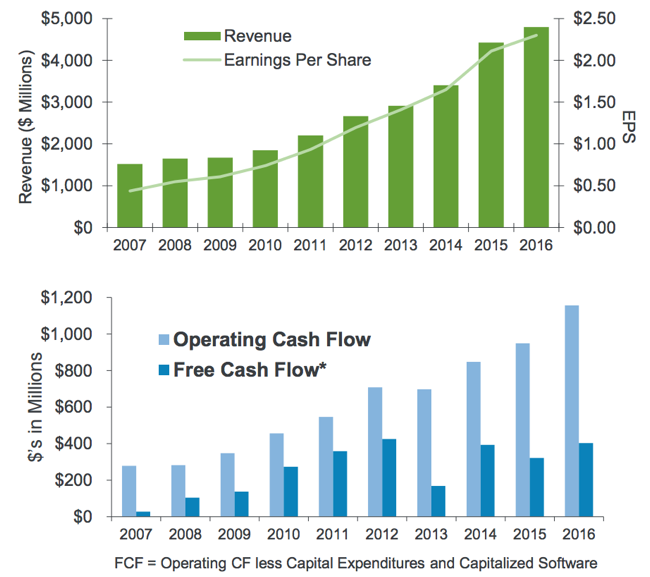
When a share price underperforms, people naturally question whether the business is still good and whether the business is still attractive for investors. To answer that question, I have attached below from the last Cerner investor community report the important financial metrics over the last decade.


That certainly looks like a good company to own, one with rising revenues and earnings, right? Yet unfortunately we are hard wired to see that the price of a stock and link that to a company's "well-being". That is unfortunately the wrong way to go about investing. In large part we have resisted the selling of what is a good business. We will hold it through the (perhaps) Obamacare repeal, which now needs to go through the Senate - Senators Set to Write Their Own Version of the GOP Health Bill. All things being equal, this would be a minor setback for Cerner, the road ahead is plenty. Whilst we were actively accumulating at lower levels, we are likely to just hold at current levels, if you have them. A great company, a wonderful future.


Linkfest, lap it up

If you are worried about Tencent's valuation and by extension Naspers valuation this graph should help calm things - China's Vast Digital Potential. Two things will happen in China, more and more people will become connected but more importantly the GDP per capita is continuing to grow. More people online, spending more! The potential is mindnumpingly huge.

Infographic: China's Vast Digital Potential | Statista You will find more statistics at Statista

I think in terms of quality internet/tech companies Naspers must be one of the top globally. It is great that we have such easy access to it and by extension one of the leading internet company's in China - China's Tencent is a sleeping giant in the global artificial intelligence race.

If a piece of art can sell for over $100 million, it makes perfect sense to me that a car (better in my opinion) can sell for the same price - Is This the Most Valuable Car in the World?. If I think that paying $100 million for anything is insane, that is another story.


Home again, home again, jiggety-jog. Whoa. Prices of metals are getting pasted, Iron Ore prices were heavily down, around 8 percent a few hours ago, I think 7 percent now. I suspect that there will be pretty big implications for the likes of BHP Billiton, Anglo and Kumba at the start. BHP was off around two and a half percent halfway through the Australian afternoon session. Wait! Tencent was off around one-third of a percent.

The Rand is a whole lot weaker. Perhaps few are convinced down there in Durban about the landscape for investment currently, or am I just being a "hater"? No, it is possibly the commodity price sell off that is impacting the Rand here this morning, Brent is also taking a paddy whack, that is good news for consumers!

French elections this weekend! We should know next week Monday/Tuesday what is going to happen with that! I suspect Le Pen will come a distant second. Hey, did you know (talking French and big things) that the Eiffel Tower was the tallest structure in the world for 41 years (1889 to 1930), and the Empire State was the tallest building in the world for 41 years too (1931 to 1972). Markets should be a little lower to start with, non-farm payrolls in the US a little later today.


Sent to you by Sasha, Byron and Michael on behalf of team Vestact.

Email us

Follow Sasha, Michael, Byron, Bright and Paul on Twitter

078 533 1063

Friday, 10 February 2017

Health Savvy

"Via the Cerner Twitter platform, the company pointed out that only ten percent of all hospitals in the US allow patients to view, download or transmit records. This was research done by Nielsen. Only 15 percent of all patients have email access to their physicians. And only 20 percent have the ability to schedule appointments online, and to see the scheduling. Everything from billing systems to aftercare of patients has not advanced to the level that we would have expected, in a society that is technologically savvy."


To market to market to buy a fat pig Stocks in Jozi, the city founded on a giant pile of gold, added as a collective nearly one-fifth of a percent by the close. It was a tale of two halves, resource stocks were having a sorry time, financials were up around nine-tenths of a percent. Gold stocks as a collective slipped two and three-quarters of a percent. The longer and shorter returns in gold stocks (drawing of lines in the sand) are a sight to behold.

Over ten years they are down 45 percent. Over five years it is not that different, down 46 percent. Over a year they are down 17 percent. None of this tells you that there were some points in the last two years that a year-to-date return had been triple digits. In other words if you got lucky or were smart, or both, you could have secured returns that some people work half a decade or more to achieve.

The commodity majors were in the losers columns, South32 (down 3%), Anglo (down nearly 3%), Kumba (down 2.38%) all at the top of the board nobody wants to be on. On the other side was Mediclinic, up over three and one-quarter of a percent. Capitec enjoyed a solid day too, up nearly three percent. Hey, of course there was the State of the Nation speech, which looked more like re-runs.

That said .... democracy, we have a platform where this can be acted out. Although, with the strong arm presence of the army and a ton of cops, and three kilometres separating the people from their platform, something looks wrong. Read Ranjeni Munusamy's piece - Calamity Zuma and the Tenth Circle of Hell. Let us hope her last two paragraphs won't materialise. As Forrest Gump said when talking sadly of his friend Bubba Blue, "That's All I Have To Say About That".


Stocks across the way, in New York, New York (where the snow was thick and a cold snap came back with a vengeance), finished the day with new records. All up similar amounts, the Dow Jones closed up 0.59 percent, both the nerds of NASDAQ and the broader market S&P 500 added 0.58 percent on the day. It wasn't all sunshine, lollipops and rainbows (Lesley Gore), Coca-Cola continues to battle with a consumer changing their patterns, notwithstanding an earnings print that met expectations of the analyst community. The stock sank nearly two percent on the day, after forecasting a fall in earnings.

Re-modelling existing products into new will take some time, I can see it already as the company pushes back on sugar. There is a fabulous yield underpin of 3.4 percent, which no doubt will be maintained (if not grow, as the share price comes under pressure), the earnings may well drag the price down. The stock has underperformed the market badly over the last five years, don't feel bad for Buffett and Berkshire, they bought the shares back in the late 1980's, around 7 percent of the company for over 1 billion Dollars.

At September 2016, the value of the Coca-Cola company stake was 16.9 billion Dollars. As a result of the buybacks over the years, their percentage (in the last annual letter) was 9.3 percent. That is 400 million shares (exactly) that cost Berkshire 1.299 billion Dollars. The company paid 35 cents a quarter last year, Berkshire got 560 million Dollars (less tax) from their stake, just to hold. Added that there is a huge tax liability, I suspect Charlie and Warren will sit on this one , i.e. they won't sell and will change as the company changes alongside them. Think bottled water and lower sugar content sodas.

The Apple market cap nearly touched 700 billion Dollars. Half a percent more, and we will be there. A trillion Dollar market cap, that may still be a number of years away, at the pace of the Apple buybacks, that may see capital redeployed to buy back shares. As such, it then becomes harder and harder, in the short term at least. If I had to throw a few hats into the ring, Alphabet is a sure contender. Microsoft would have to double from here. Berkshire is fourth in line with a market cap of a little over 400 billion Dollars. Yip, we are going to have to wait a while for the trillion dollar company.


Company corner

Cerner, the specialist information technology healthcare company reported numbers after the market closed. Last year was their toughest year in a long time, spend on hospital systems slowed as uncertainty around government action in the healthcare sector increased. The fewer benefits for the public at large, from a healthcare point of view, will mean that the hospital industry will have to operate on lower costs with possibly lower outcomes. These numbers are for the full year and the last quarter, let us look at the FY numbers to get perspective. Revenues hardly budged at all, clocking 5.446 billion Dollars. The revenue backlog did rise 12 percent, which is pleasing, to nearly 16 billion Dollars. There was a shift in the sales mix to more annuity business, services and support and maintenance at the expense of new sales. This reflects what we were talking about above.

Expenses were up 11 percent when compared to the prior year, which is not "small", some of that included voluntary separations, which also impacted on operating margins. For the full year, 2016, adjusted EPS clocked 2.30 Dollars, up 9 percent from the year prior. The company bought back shares to the tune of 700 million Dollars last year. They are not paying dividends at all, for the duration of the listed entity, they have not paid any dividends. And with the growth trajectory set at quite a "high" level, I suspect that we are unlikely to see a dividend any time soon.

Yet there was not much by way of growth over the last year, which explains why in large part the stock has trended lower and lower. At the after-market price of 51.65 Dollars (down over four percent), the stock trades on 22.45 times earnings and is not delivering the earnings growth that the market expected. At least not in the short term. Guidance, let us have a look at that quickly. For the full year, the company expects revenues to grow at 8 percent and earnings at the midpoint of the range at (2.44 to 2.56 Dollars a share) at 9 percent. That is a little over 20 times earnings at the midpoint, which puts the PEG ratio at over 2 times, which is by no means cheap.

Often when analysing a business and trying to discern (which ironically is the name Cerner in Latin) whether it is a good investment or not, you need to look at the management, the product and the market and try and work out whether people are going to need more, or less of their products in the future. Margins and cash flows are also an important part of the puzzle. For the most part, hospitals and paperwork go hand in hand. The founding premise of Cerner is to make healthcare easier, eliminate humans in critical areas of hospital and doctor to patient service (from dispensing to administration of medicines, to critical care and monitoring) with the same objective, to improve the outcome. And by that, eliminate mistakes, cut down on paper and improve productivity. Who wouldn't be thrilled by that outcome?

Via the Cerner Twitter platform, the company pointed out that only ten percent of all hospitals in the US allow patients to view, download or transmit records. This was research done by Nielsen. Only 15 percent of all patients have email access to their physicians. And only 20 percent have the ability to schedule appointments online, and to see the scheduling. Everything from billing systems to aftercare of patients has not advanced to the level that we would have expected, in a society that is technologically savvy. That is where I think that the business has huge potential. The stock price might however not be "right" at this point in time. If you hold the stock, expect that the market is going to take a dim view on the outlook. Know that you are in the early stages of what will become a huge business, the complete digitisation of the industry. And that will be better for all of us. Hold. A good company, in a good sector, going through a bit of a funk.


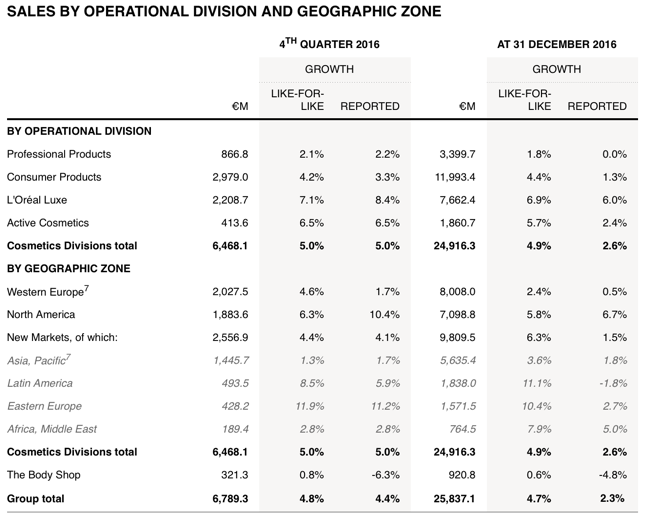
L'Oreal reported numbers for their full year last evening, after the market had closed in Paris. The company continues to attract market share across all territories, sales grew 4.7 percent like for like to 25.84 billion Euros, earnings per share increased by 4.6 percent to 6.46 Euros per share. For the purposes of this exercise, when talking about valuations, we will reference the Paris price, which is 174 Euros a share. The stock trades at a pretty lofty 26x earnings, which is not cheap at all, the company has delivered in what has been a pretty tough operating environment. The company has four major operating divisions, you can see the breakdown via a previous message on the business - L'Oreal 3Q numbers - steady growth. The dividend has been jacked up by 6.45 percent to 3.30 Euros, maintaining the nearly just under 2 times dividend cover.

In terms of profits geographically, Western Europe is their strongest market in terms of profits relative to sales. The company always has the most fabulous revenue by geography and revenues by segments. All the divisions are of a similar operating profit as a percentage relative to sales, around 20 percent. It is a key metric of theirs. The company spends a large slice of sales on telling you how amazing the products are, I guess that it is a very competitive market.


The company is looking to sell the Body Shop, this is not new news. They are looking to fetch around 1 billion Dollars, it is going to be hard to find a buyer for that business, as a recent Bloomberg Gadfly article pointed out, it is neither hipster nor is it new, and it is definitely not premium - Making The Body Shop Great Again.

The investment thesis is pretty simple, the company is the leader (around 28-29 percent cosmetics) in a growing market globally, around 3.5 percent. The cosmetics market is growing at a faster click than global growth, there are many more woman enjoying soft luxury than at any other time in history. The company continues to expand their presence across all the social media platforms, they have multiple platforms across Instagram and Facebook, as well as Twitter. Simple things, such as tutorials for applying makeup, new products and product range. The company now has around 1000 people working on these platforms, they certainly take it really seriously, it is a great feedback loop.

This is a deeply loyal product for many people, once you trust and apply the product, or use the shampoo and associated hair care, you are likely to stick with it for years and years. The share price performance has been pretty pedestrian, keeping pace with a weakening Euro to the US Dollar. We hold the unsponsored ADR. To illustrate the point, the share price performance in Euros over five years has increased 114 percent, whilst the Dollar based price is up "only" 73.9 percent. I will take that Dollar return any day of the week. A currency unwind, should we say, would be helpful for our Dollar investments in a European currency denominated company.

This is a great defensive and growth business, their products are always going to be used. The company will continue to grow as global GDP rates grow, and remains a key pick in our consumer based investment theme. We continue to accumulate.


Linkfest, lap it up

I really didn't know what to make of this, whether to be amazed or whether it was going to be the "rise of the machines" (as per the posters on the walls), or whether to think this chap was completely crazy. Either way, they are not the first and they won't be the last - Silicon Valley Hedge Fund Takes On Wall Street With AI Trader. What is most interesting is that this guy has a connection to the development of Siri and also has little finance experience up to this point.

When I had finished this article I wasn't sure what to make of Jimmy Iovine. What I was sure of was his passion and his ability to really think (and act) differently. One thing is for sure, streaming music has changed the way we all consume music and no doubt Apple will keep up to date with the trends. How Jimmy Iovine Plans to Take Apple Music to New Heights.


Home again, home again, jiggety-jog. Stocks have started better on this side, the Japanese market flew today! We live in interesting times my friends.


Sent to you by Sasha, Byron and Michael on behalf of team Vestact.

Email us

Follow Sasha, Michael, Byron, Bright and Paul on Twitter

078 533 1063

Wednesday, 2 November 2016

Healthy Spending


"I feel that the company is in a space that will continue to see massive growth. GDP percentage spend in healthcare in the US is expected to continue the upward trajectory. They have many more territories in which to operate and are one of the real quality operators globally. Non-U.S. revenue represents only 11 percent of Cerner total revenue. The bookings and backlogs are huge,"


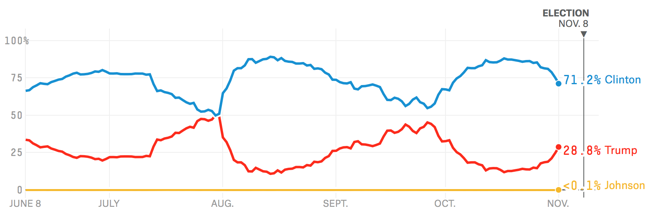
To market to market to buy a fat pig With the possibility of a Trump victory in the US elections closer than last week thanks to the new FBI email investigation against the other more desirable candidate, Mr. Market shuddered and really didn't like what they saw. How is this possible? Well, those are polls. For what it is worth, in the prediction markets, Clinton still holds a very strong chance, far stronger than Trump, check it out (thanks Paul for the link): Who will win the presidency? As of this morning, Trump's chances of winning, according to this measure is only 28.8 percent. Which is actually higher than Lloyd Christmas ever marrying Mary Samsonite. I wonder about polls, I suspect that everyone feels a little burnt post Brexit and the polls, elections in the UK too. Here goes, the chances thing from FiveThirtyEight:


The story overnight on Wall Street is that with the race tightening and the predictions market itself seeing a closer battle (this hardly seems close, does it?), safe haven assets are catching a bid over traditionally riskier assets. i.e. Japanese Yen, US Treasuries and the Dollar are in, equities I am afraid you are the weakest link. And the Mexican Peso, which has also been some sort of barometer for the US election is at a two month low. This morning Asian markets find themselves at a 7 week low. Never-mind earnings sports lovers, never-mind that the World Series Baseball is tied at three games apiece, never-mind that "City" (the blue team from Manchester) managed to pull one over Barca last evening, never-mind that OPEC may not be able to pull off a supply agreement, stocks are all about the US elections right now. We just have to live with it.

Session end, the Dow Jones Industrial closed 0.58 percent lower, the worst levels since mid September (that is not such a long time ago), the broader market S&P 500 lost 0.68 percent, and the nerds of NASDAQ just a smidgen more than that. Energy was the only major sector that ended in the green, with Chevron and Royal Dutch Shell (up nearly 5 percent) being winners there. Apple and Pfizer were noticeable losers, the maker of wonderful devices (that is Apple) is seeing heat from the investor community in China and also may be dropping the price of Apple Music. I guess to attract more and more people. I use Apple Music exclusively and think that the product is amazing. Pfizer, that stock was lower after after their results, the market may see a nearly four percent yield, the growth, well, that appears to be missing for the time being.


Back home, where the heat is still being turned up on the weather front and in the courts (all rather complicated) stocks produced a winning day. Resources post the Chinese PMI number were the drivers on the day, it was still a pretty broad based rally. AngloGold and Amplats were monster winners on the session, Shoprite and Woolworths were at the other end of that stick! Most of the moves on the day were higher, winners outpaced the losers 2 to 1, more or less. Jeepers, in all the years of writing this, that may well be the first time that I have ever said that. Repeat, this is not a market blog. A small factoid, did you know that the market capitalization of Steinhoff is nearly double that of Old Mutual? Bet you didn't! The market cap of Standard Bank is also double that of Nedbank, did you know that? And to think that the two entities could be one, if it wasn't for the pesky regulators. Ha-ha! And Aspen is half the size of Anglo American, in market cap. So there you have it.


Company corner

Cerner, the IT healthcare services company, reported numbers and issued guidance for the coming quarter. For shareholders who are not looking to add to their positions, I am afraid the guidance and the numbers themselves fell short of expectations. Obviously the market was looking for more, the stock was down around 6 percent post the market close, i.e. in the aftermarket. What does this business do exactly? This is a business that uses current technology to make healthcare systems easier to use.

Eliminating paper and human error, making the entire ecosystem digital from the time you enter the ambulance to the time you are discharged, Cerner can be part of the process. For the better. The company offers solutions to all size healthcare providers to make lives easier for all concerned. Safety of patients, being able to serve those same said patients with high quality care and eliminating wasteful expenditure along the way, making the business more profitable (and by extension more resources elsewhere) means that everyone gets what they are looking for.

The company manufactures software that reduces human error, essentially. By working together with the healthcare staff and administration, they eliminate incorrect procedures and help the healthcare professionals keep a clean sheet means less litigation (yes, true story) and most importantly, the best outcome for the patient and their loved ones. And by using the internet (the cloud) the resources are able to be best utilized at the healthcare facility. i.e. if patient X needs Y and pronto, the pharmacy is already issuing the prescription that the doctor ordered, and the delivery would happen soonest. And therapy X would be facilitated and hey presto, all parties would save time and be kept notified of the progress of the patient. Neat, hey? Think sharing of clinical trials too.

The company is innovative, is licensed in around 25 facilities across the globe, in 30 countries. As per the annual report, they do business in "hospitals, physician practices, laboratories, ambulatory centers, behavioral health centers, cardiac facilities, radiology clinics, surgery centers, extended care facilities, retail pharmacies, and employer sites."

Their strength also lies in their ability to crunch the data being generated. In the 2015 Annual report the chief, Neal Patterson said: "In 2012, digital health care generated an estimated 500 petabytes of data worldwide. By 2020, that number is expected to grow to 25,000 petabytes. The only missing ingredient, then, has been a systematic way to analyze the data and make it actionable in providers' workflows. Fortunately, as we saw this situation developing in the early part of this decade, we knew a good health IT systems company that could take care of the problem."

And then in his closing segment of the CEO's letter in the 2015 annual report, Patterson continues, pointing to the whole prevention is better than cure theme that is currently taking hold: "The next era in health care is a shift toward prediction and prevention, personalized engagement and new types of interactions that are both continuous and contextual. Because Cerner invests in the future, we continue to arrive at the right place and time with systems that address real needs in health care."

Onto results for the third quarter of the previous financial year. Revenues were lower on the comparable period, a tough comp as the previous year had grown by 44 percent, 10 percent lower than the comparable at 1.434 billion Dollars, and unfortunately this was below guidance. Revenue guidance for the next quarter is 1.225 to 1.3 billion Dollars, also below what Mr. Market was looking for. Adjusted diluted earnings per share clocked 59 cents, below Mr. Market consensus of 60 cents. Guidance for the next quarter was 60 to 62 cents worth of earnings, also below the market consensus.

That is exactly why the stock was "downgraded" by Mr. Market, down 6 percent as we said earlier. The early guidance for 2017 looks OK to me, revenues for next year at the midpoint (between top and bottom) expected to be 11 percent better than revenues for this year and adjusted diluted earnings per share to be in the region of 2.50 to 2.70 Dollars. That means that at the indicated opening share price, the stock should trade forward on 20.9 times. I guess with revenue growth lower than before, the market has adjusted away from growth to a more "manageable" multiple.

I feel that the company is in a space that will continue to see massive growth. GDP percentage spend in healthcare in the US is expected to continue the upward trajectory. They have many more territories in which to operate and are one of the real quality operators globally. Non-U.S. revenue represents only 11 percent of Cerner total revenue. The bookings and backlogs are huge, the company has an enormous amount of work to do and could surprise always to the upside, this time around they disappointed their own high standards. We continue to hold the stock of what is a fine business, and ride out the current weakness.


Linkfest, lap it up

As sales of sugary drinks fall, product developers are coming up with new variants to try keep customers and lure old ones back - Coke Ginger designed to tempt health-conscious Australians with new infusion. Does ginger flavored coke sound more healthy to you? Would you drink it?

The key market that Amazon wants to break into is the grocery business. It is a huge part of peoples monthly budgets and it is a regular spend, unlike buying books or TVs - Affordable, Quick Delivery Is Key for Online Grocery Sales. The key to this market is speed of delivery which is where all the billions spent on distribution centers will come to the fore.

Is this competition at its finest?. New products normally come to market at a premium because of little competition. Then as the competition rises the price falls until the product becomes a commodity and sells for little more than the production cost - Your brilliant Kickstarter idea could be on sale in China before you've even finished funding it.


Home again, home again, jiggety-jog. Disaster struck this week, in the form of the opening hour of JSE trade being in a vacuum. In other words, daylight savings in the modern world means that we "lose" a hour of trade as JSE volumes are down due to clocks in Europe and the UK being turned back an hour. A reduction of energy usage was supposed to be the main reason, plus also encouraging late night summers and athletic participation. Surely in the modern world, with heating and cooling and flexi-hours, it makes more sense to keep your time?


Sent to you by Sasha, Byron and Michael on behalf of team Vestact.

Email us

Follow Sasha, Michael, Byron, Bright and Paul on Twitter

078 533 1063