Wednesday, 10 August 2016

Slow grind records

"The US markets also fizzled out towards the end of trade, yet stocks still remained in the green, only if just. And it was another record intraday high for the S&P 500."


To market to market to buy a fat pig I would prefer, from a logistics point of view, for all public holidays to be on a Friday or Monday. Period. In that way, productivity can be higher, rather than disruptive to normal events. Politicians may work hard, but offer very little from the view of making stuff or offering a service that we had to pay for. If all government services were at a market related rate, what would the cost of your electricity, water, garbage removal, etc., be if there was a viable, and economic alternative. The flip side of that coin is, if local government didn't offer the service, nobody would live in that place. We are off the point. I suspect that we can celebrate public holidays and vote on days not in the middle of the week.

Overnight Michael Phelps backed his killer stare up and smoked everybody, including our own Chad le Clos. The US markets also fizzled out towards the end of trade, yet stocks still remained in the green, only if just. And it was another record intraday high for the S&P 500. In the end, the Dow Jones Industrial Average and the S&P added fractions of a percent, adding 3.76 and 0.85 points respectively, meaning when rounded to the nearest one decimal place both markets were up 0.0%. The nerds of NASDAQ added nearly one quarter of a percent, Apple still marching steadily forward.

Since Apple reported quarterly numbers on the 26th of July (after the market closed), the stock is up nearly 12 percent. There has almost not been a down day since. And yet the stock still trades on a less than 13x historic multiple. The BusinessInsider had several interesting articles on Apple, including the headphone jack (or lack thereof) for the iPhone 7, this one caught my eye - iPads are doing better than expected, but tablets are still on the decline. The best problem that everyone has is that the tablets all work so well and perform their functions, there is little or no need to upgrade furiously. Until there is a huge form change.

The Pound continues to get smoked, stimulus and low rates and the central bank warning of a slowing economy is at some levels reflected in the numbers, other numbers continue to impress. The tourism sector in the UK continues to benefit from a weaker Pound. Job hires, not so much. We shall see the medium term impacts, we shall see if the economic impacts become more and more noticeable as time goes by. Back where local is lekker, stocks rose a touch on Monday, up just over one quarter of a percent.

Steinhoff was the big news of the day. We will see how that transpires, the acquisition target Mattress Firm shot up over 110 percent to the offer price of 64 Dollars a share, the graph looks like the "El Capitan". Not the operating system, rather the Yosemite cliff. We had rock climbers at school, the club was huge, the teacher in charge always used to say "fully". He had a long red beard and scraggly hair. He was our English teacher too, a heavy lefty with vegan tendencies, he opened our minds to the rest of the world. That could have been the motto for Steinhoff, "fully" Marcus Jooste, "fully". The only fully you don't want to see is fully priced and then overpaying.

Woolies were also in the news, they sold their David Jones head office building in Sydney, which is adjacent to their department store. The head office of David Jones will move to integrate with the rest of the business in Melbourne. The funds received will be to upgrade their department store in Sydney. And no doubt staff will be cheaper in Melbourne. I don't know, let us know, if you live down under. Are the jobs and the cost of living very different from Sydney to Melbourne. One gets the sense that Sydney is more expensive, Melbourne is more attractive. Definitely from a sport point of view. Woolies expects to save 10 million Aussie a year, whilst still rolling out the best of retail in the Southern Hemisphere in an 11 level shopping mecca.

We are "owed" Woolies results on the 25th of August, that is just around the corner. We will review then, the trading statement has pretty much fleshed it out, not too much to expect. Whilst the stock has "done well" recently, year to date the price is down 10 percent. The company doesn't really have a real comparable business here locally, can you really compare them to Pick 'n Pay or Shoprite, or Massmart or the Foschini Group? Whilst they broadly fall in the same space, they are all different offerings. Buy the company, not the share price.


Company corner

At the beginning of the last financial year, 1 April 2015, the website synonymous with online booking, Booking.com (parent company and listed entity Priceline.com), had 670,000 places to visit. On August the 5th, 16 months later, the company announced that they had Added Its One-Millionth Property in Nantucket, Massachusetts. Of those, as you can see from the release, there are 23 million bookable rooms around the globe, with 7.2 million of those being homes, apartments and villas. Half of the total properties are NOT hotels, which in a sense allays many peoples fears that Airbnb will eat their lunch. They are all eating the same lunch. Besides, the biggest listed competitor in its space is Expedia, which is only 11.6 percent the size of Priceline.com.

Priceline has a market cap of 73 billion Dollars as of the last close, that is monumental in itself. And yet, the stock is neither cheap, nor is it expensive. At 27 times historical earnings and with the analyst community predicting over 68 and a half Dollars of earnings, the stock trades forward on just over 20 times. Growing earnings and revenues at a pretty breakneck speed, the same said analysts have the company making nearly 80 Dollars a share next year, and the multiple unwinds to just above 17 times earnings. Currently the company pays no dividends to their stock holders, growth is the current focus.

Herewith from the annual report from last year, these are all the key metrics which shows the meteoric rise in bookings and profits over the last 5 years.
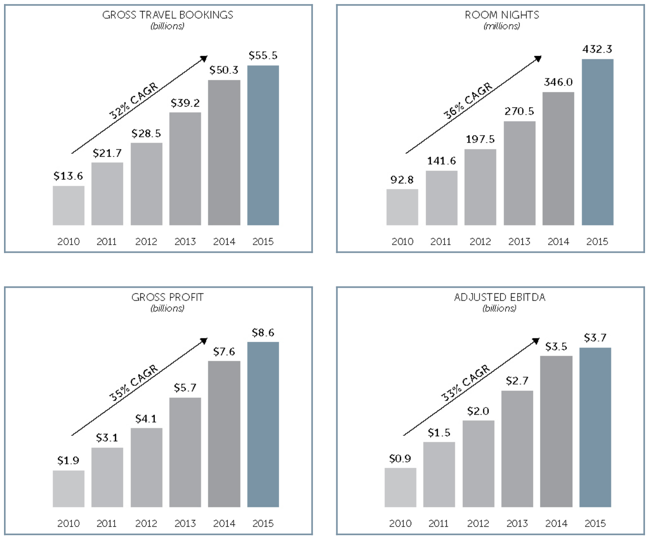


So how does Priceline.com earn their money? The annual report breaks it into a few categories, processing fees (on behalf of smaller places of accommodation), commissions earned on the facilitating of accommodations, hires of rentals, ship cruises, as well as advertising revenues earned by KAYAK, one of their multiple platforms. They also recently, having acquired OpenTable, earn reservation revenues. And what do they plan to do, in order to continue to grow their revenues? Providing a great booking experience (they may want to work on that, it is easy, it could be easier), they are going to continue to partner with other travel providers, as well as restaurants (get the complete package), as well as investing heavily in other platforms. For instance, as they point out, they invested in Ctrip, a Chinese mainland operator. CTrip is actually listed in New York, and has a market capitalisation of nearly 20 billion Dollars.

Google and Facebook may well roll out large booking systems. I was quite interested when reading about online booking behaviours. It is different for business travel over personal. In business travel, over half of people in North America book their own business trips - Business traveller booking behaviours.

Tripadvisor (a competitor of sorts) had their 6 key travel trends for 2016, in which Trend#6 was quite important for me: "93% of hoteliers said that online traveler reviews are important for the future of their business" and "Online reputation management is still the biggest area of investment for accommodation owners in 2016, with 59% investing more in this area than they did the previous year."

Which means that more and more travellers will trust websites like Booking.com more than any other platform. The fact that the property is rated 9 out of ten and you can see the comments (petty or not) and the interaction with the management, means that all the dirty laundry is laid out bare. For all to see. The consistently higher you score, the more money you make, the more you are likely to promote your property on the website. All the reviews are for actual guests staying there, you only get a review request if you book through the platform, or are invited by the establishment.

So here goes, the last set of numbers: The Priceline Group Reports Financial Results for 2nd Quarter 2016. Revenues grew by 19 percent to 17.9 billion Dollars, gross profits increased 16 percent to 2.4 billion Dollars. That is nothing though, this is the dominant online business, and global revenues for the travel bookings industry is at 1.3 trillion Dollars. Their, Priceline.com, share is less than five percent. As such, there is plenty of road to run here. We continue to accumulate a growth business at a very reasonable multiple, relative to their growth prospects.


Linkfest, lap it up

Knowing your time frames before committing a cent to the market is important. If you know that you are investing for the long term, when the market plus back it may not feel good but you can still sleep well at night - Rules-based tactical vs wizardry and witchcraft. If you don't know your goals and time frames before hand, statements like this will scare you. "As a result, we downgrade equities tactically to Underweight over 3 months, but remain Neutral over 12 months."

I can see similar technology being used in an Apple watch in the future - An electronic temporary tattoo will warn people if they've had too much to drink. Imagine, your Apple watch senses that you have had too much to drink, it deactivates your Apple car and calls you an Uber instead.

Sticking with the Olympic fever, here an estimation of some of the incentives countries give to their athletes who win Gold. The US incentive may seem low compared to other countries but the athletes that win gold representing the US also generally get larger endorsement cheques - Some Athletes Are Chasing Huge Gold Medal Bonuses

Infographic: Some Athletes Are Chasing Huge Gold Medal Bonuses | Statista
You will find more statistics at Statista


Home again, home again, jiggety-jog. A couple of questions for the loyal readers. Would you like to see more videos done on stocks via the Instagram platform? For the time being they have been sporadic, far and few between. A loose and informal style? Have you signed up for all of our platforms? Do you follow us on Twitter (see below). We have both a Facebook page (like us) and an Instagram platform. And lest we forget the entertaining Blunders videos, the weekly one delivered on Friday - Blunders - Episode 25. Sign up for all these platforms, to never miss a beat. Let us know, more videos or not? We used to be very active in that space, and went a little quiet in that regard. Perhaps all people need nowadays is a 30 second clip of how things are going, is this one a good one, or not. Markets across the globe are a touch higher.


Sent to you by Sasha, Byron and Michael on behalf of team Vestact.

Email us

Follow Sasha, Michael, Byron, Bright and Paul on Twitter

078 533 1063

Monday, 8 August 2016

Doubling down on the sun

"As Musk points out, it would create the world's only integrated sustainable energy business. Energy generation, storage and then conversion to mobility (panels to batteries, batteries to motor vehicles) would see an all in one solution. The installation cost per Watt produced continues to fall, the sad truth is that Musk is a dreamer (like Bezos), profits come later. He believes that they will come."


To market to market to buy a fat pig Up, up and away. Records all around, as Wall Street climbed higher Friday as a result of a well received "jobs report". Officially the report is known as The Employment Situation. You can read it and see that the US economy, according to the Labor Department (without a "u") added 255 thousand jobs for the month of July, just past. Healthcare and services related employment in the biggest economy in the world, remain strong. There were revisions for the two months prior, both in a positive direction.

I am not the biggest fan of this report, this is, it must be remembered, the market go-to report each and every month. The most highly anticipated report since the last one, that is always how it turns out. This one is so important, blah-blah-blah, the multiple folks on the box tell you. I always ask people when they highlight the importance of this report: "what was the headline number 6 months ago"? The answer is almost always a blank stare. Round these parts we like and prefer companies and their results/news. I did see something that validated the strong jobs report, speed read it: Chemical activity hits a new high.

A strong report of course sees the likelihood of a rates increase sooner. That is best left to the Fed to decide. Speculating on that is like posting your favourite Springbok or Bafana Bafana lineup on Facebook. The truth is that whilst someone may care (and strongly disagree), the selectors and coach don't give a rolling donut what you think. Good tweet over the weekend (poor Lions, it was always a tough call), it went like this: "If only the Lions had their phones on the field, then they'd be able to see all the helpful advice on Twitter from the real rugby experts." Replace Lions, field and rugby with Fed, (in) monetary policy meetings and economy.

At the bell the Dow Jones industrial average was up just over a percent, ditto the nerds of NASDAQ (5227.23 is your all time high). The broader market S&P 500 closed at the all time high, ending the session up over four-fifths to 2182.87. Records, as we know, are meant to be broken. Even steroid infused ones from yesteryear. Wow, the Olympic Games are awesome, every four years I find myself watching and enjoying volleyball, handball and a multitude of interesting looking sports that are only watched with that regularity. Sadly.

Back on the local front, where Mzansi didn't know that they would wake up Monday morning with a silver medal (Cameron van der Burgh you good thing), let alone who would be running some of the major metros across the depth and breadth of the country, stocks didn't act accordingly. A stronger local unit had everything to do with it, I guess. This morning the Rand is at 13.70 to the US Dollar, 17.89 to the Pound Sterling and 15.21 to the Euro. Yes sports lovers, get your hands on some forex, invest offshore if you can, if you spread warrants it. Over the last year, the Rand is still around 8 percent weaker to the US Dollar.

At the bell, the Jozi all share index had closed just over one-third of a percent weaker on the day. Industrials lost over half a percent on the day, stocks like AngloGold Ashanti, Amplats and Bidcorp were the worst three of the majors, BHP, Glencore and Shoprite (new 52 week high) were the best of the top bunch.

There was an FT article (that Bright alerted us to) over the weekend, indicating that Steinhoff were looking to make a go for US retailer - Steinhoff targets US with $3.8bn deal for Mattress Firm. Subscription only, sorry, that FT. The official release from Mattress Firm is here - Mattress Firm To Be Acquired by Steinhoff International for $64.00 Per Share in Cash. They continue to "bed" down deal after deal. They are looking to get into bed with majors across the globe. Steinhoff continue to acquire where they see value. Whilst this seems an excessive price (and it is), the stock is trading today at the same price as in January 2012. The premium is where the stock traded at in October 2014, same price. Since then the going has been tough.

Who is Mattress Firm? In the Fact Sheet about the group, there is a projection, and perhaps that is why you can see Steinhoff wanting to pay this premium:


Mattress Firm, firm offer, firm plans, there is no Hoff like the Steinhoff. As the release says: "The merger agreement, which has been unanimously approved by the Mattress Firm board of directors and the management and supervisory boards of Steinhoff, will create the world's largest multi-brand mattress retail distribution network." Wow. Not bad for some humble beginnings down at the bottom end of Africa. Steinhoff now operate in 30 countries with 40 brands. And are not sitting still any time soon. We watch with more than a little interest, this is becoming a more and more important holding for our clients.


Company corner

MTN Group reported numbers for their half year to end June this morning (Friday morning). It has been a tumultuous time for the mobile operator, lurching from one problem to the next, Iran and the hyperinflation (and sanctions, inability to externalise money), Nigeria and the whopping (if not borderline stupid) fine, price wars in the local market. There is a time when one questions the thesis over and over.

Hindsight is better than Maverick and Goose's flying skills (C'mon, you know you loved that movie), it would have been better to own Vodacom. And Telkom at some level. Water under the bridge, the price you see in front of you today reflects the ability of the business in the future, as reflected by the shareholder base at this point.

It is far easier to report back on a business when the stock price does well. Too often, the chattering classes draw conclusions between share price performance and the company. Including on whether the quality of the management team is good or not.

As a result of having incurred a hefty fine from the Nigerian authorities (whether they called their bluff or not is another matter), and huge loss of value for the asset management community, suddenly casts a negative light on the management team. With an element of righting that wrong, management ultimately is where the buck stops. Sifiso Dabengwa fell on his sword, Chairman Phuthuma Nhleko took over the reigns and more recently the management team has been strengthened with a quality team that looks distinctly like the colour of investment banking (and deal making).

The fact that data continues to grow sharply (at the expense of voice and by extension EBITDA margins) is a testament to management's willingness (and shareholders to part with the capital) to aggressively roll out the infrastructure in order to meet quickly changing handset requirements (Capex spend was R13.77 billion). Mind you, this is definitely not a company specific thing.

I saw an astonishing moving .gif the other day, from a tweet, of the populations of Nigeria and the USA over the coming decades, as well as the decades past. This is how #Nigeria will overtake the US as the world's 3rd most populous country (Currently 7th).

That is all very nice to suggest that population projections result in ARPU increases in a hurry. The currency has being weighing heavily and I am sure that many investors are getting impatient. We will continue to evaluate the results and provide shareholders with the feedback and guidance they deserve.


Tesla reported numbers for their Second Quarter 2016 last week, as we were voting and worried with the weighty matters of democracy. Tesla are equally worried with the weighty matters of sustainable energy and climate change. One of the best and most sensible things Elon Musk said was that the best and most reliable energy sources known to mankind was the sun, yet we hardly enhance the full potential.

As you would know, Tesla is currently in the process of acquiring SolarCity, another Musk associated company, for 0.11 Tesla shares per SolarCity share. Which roughly values, or valued SolarCity, at 2.6 billion Dollars when the final deal amount was announced. The expected ownership of the "new" Tesla will be approximately 6.5 percent of the SolarCity shareholders (which include Elon Musk) and 93.5 percent the balance of the Tesla shareholders. The deal is expected to close in the fourth quarter this year.

As Musk points out, it would create the world's only integrated sustainable energy business. Energy generation, storage and then conversion to mobility (panels to batteries, batteries to motor vehicles) would see an all in one solution. The installation cost per Watt produced continues to fall, the sad truth is that Musk is a dreamer (like Bezos), profits come later. He believes that they will come. Now, when you run a public company and you are responsible for other peoples money, you will draw major criticism from all quarters. Including the naysayers, it can't be done they will say.

He (Musk) has done a lot already. He has changed the mindset of humanity and their adoption of electric vehicles (EV's, the only acceptable acronym, OK?), yet one feels that we haven't quite scratched the surface yet. Heck, Tesla only delivered 14,402 vehicles last quarter. Less than the 17 thousand they targeted. If you needed a reminder, the global sales number last year was (according to The International Organization of Motor Vehicle Manufacturers annual sales table - French acronym OICA) 89,677,983 in 2015. That is either a lot, or not that many, depending on the way you look at it. I plan to have as few motor vehicles as possible in my life, they are a tool, not a necessity, say, like a shower or bed.

Even if Musk reaches what looks unobtainable, 90 thousand this year, Tesla would still only be 0.1 percent of global production. It is not surprising that one doesn't see these vehicles on the road, you have to visit high net worth global areas. It is not as if the company sits still, hell no, they are busy adding a new retail location every four days in the next two quarters. The plan is to generate huge interest and the ability to meet it will be ramped up over the coming years.

In the mass car department, Musk updated the audience in the shareholder letter -

    "We have completed the design phase of Model 3 and released Model 3 for tooling, production planning and validation. The Model 3 capacity expansion will reflect our initial efforts to apply our "machine that makes the machine" philosophy to vehicle manufacturing, and demonstrates our intense focus on volumetric and capital efficiency. Some Model 3 production equipment is already on line, including initial capacity in our stamping and paint centers. Later this year, we plan to begin construction of new Model 3 body and general assembly centers."


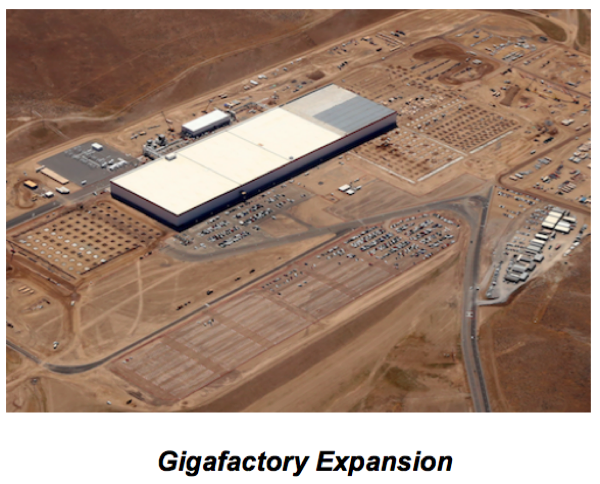
If you are owning this company, you are essentially owning an option on the future, a changing consumer pattern and adoption of EV's (all of which look intact) and a huge bet on the masterplan. The GigaFactory is a sight to behold. Musk showed an aerial view of the progress, the inside (you have seen the pictures) is more impressive:


The outlook segment is pretty hard running, Musk wants to produce 2200 cars a day for the third quarter and 2400 a day for the fourth quarter, in order to reach that 50 thousand run rate for the second half. The company is still planning on investing 2.25 billion Dollars in capex for the full year, that new production line and solar factory battery producer don't look cheap. Whilst revenues grow like gangbusters, so do costs. Musk and Tesla have grand plans, humanity needs people like this.

With a market capitalisation of 33 billion Dollars, the company is certainly expected by the investment community to do amazing things. They, not unlike another technology company that sells hundreds of millions of iPhones, make beautiful products. Which are easy to use and simple looking and quite simply have awesome features. Know that the investment is not for everyone, you need a high tolerance for risk. Musk himself stuck his own money in at the beginning as he wasn't sure it was going to work. The biggest ever weekend of initial sales of a consumer product (the Model 3 launch) in history tells you the consumer is chomping at the proverbial bit. Accumulate as a high beta stock at the fringes of your portfolio, if your risk tolerance is up for it.


Linkfest, lap it up

Amazon's air fleet takes to the skies. Being able to do more of the delivery work themselves will help them bring down their operating costs - Amazon Reveals 'Prime Air' Cargo Jet. It is a very nice paint job.

We have spoken a few times about the rise of bottled water, most of our conversation has centred around the move to water because it is healthier than soft drinks. It seems that water infrastructure is another reason, old pipes are leading to tap water not being safe to drink - Bottled Water to Outsell Soda for First Time This Year

Not all accents were created equal when it comes to speech recognition software, Google is trying to fix this - Google is seeking thick Scottish accents

There is Olympic fever in the air, I think the article's title speaks for itself - A refugee who was swimming for her life to escape Syria one year ago is now swimming in the Olympics


Home again, home again, jiggety-jog. My personal favourite is when sports fans shout at the tv and tell the players how rubbish they are. I can't help myself and I laugh furiously. The one being paid spectacularly for their talents is the one tasked with the job. Imagine if your u16c team at school (the last time you partook in that particular discipline) had three minutes against the other team. More importantly, imagine if crowds of people watched you from a distance at your workplace and criticised your work in the same way? Ha ha, that is the evolution of Big Brother, Endemol should give that one a go!

Stocks are mostly higher across Asia, Japanese stocks have rallied hard, up over two and a half percent. US futures indicate another better open for them on that side. We should catch a bid here today. Do not attempt to ask me about politics, I have no idea. That is the domain of those with sharp tongues, short memories with teflon coated skin. Nothing sticks.


Sent to you by Sasha, Byron and Michael on behalf of team Vestact.

Email us

Follow Sasha, Michael, Byron, Bright and Paul on Twitter

078 533 1063

Thursday, 4 August 2016

Healthy Software

"At the end of the day, you are buying a software solutions provider to the healthcare industry, and as such, this is a pretty niche market. We continue to believe that legacy systems across the globe will be replaced with better cloud based solutions and practical cost saving solutions that will encourage healthcare groups to adopt these types of software"


To market to market to buy a fat pig That was a busy day, Thursday. In part it was catch up, the stronger currency as a result of a weakening Dollar, led to local retails and banks getting a proper lift, whilst Rand hedges came under pressure. That was understandable. As I sit here and write this, the Rand is last trading at 13.69 to the US Dollar, 17.94 to the Pound and 15.24 to the Euro. Remember the Barmy Army song, I have got 22 (and then 23 and then 24) Rand to the Pound late last year, and earlier in January? She gone, as they say in the classics. Emerging market excitement has returned and local retailers and banks all look attractive.

The upshot is that when the big uber caps like British American Tobacco don't do well as a result of the currency translation, the weaker Pound is certainly good for their global businesses, however. The stock in Pounds is up mid teens since Brexit, in Rand terms it is down 4 percent. Does that make them a "good one" or a "bad one"? The market has significantly upgraded the stock, the earnings are likely to be given a big boost by the weaker reporting currency, the Pound.

Yesterday the bank of England cut rates to an all time low. The pensioners who voted Brexit now are stuck with lower interest on their cash deposits. And the lower income groups that voted against immigrants still can't afford a loan as the income levels are not what they should be, even with the lowest rate on record. When searching for information on the oldest Italian bank (Monte Paschi) that is wobbling all over the show, I found that the Bank of England was one of the oldest banks in the world, 322 years old at last count. The original purpose was to act for the government, the fact that democracy existed that far back (1694) is a testament to the durability of the model. Although, to be fair to the word democracy, you only voted if you were rich and a man, hardly counts "free and fair", right?

Since Brexit, the Pound has lost nearly 11 percent to the US Dollar. More worrying, and this may well be very short term, permanent job placements in the UK fell at the sharpest pace since May 2009. This may be a wait and see type scenario, stick it in the unintended consequences drawer. To finish off the markets segment, stocks locally as a collective closed a handful of points higher, up a whole 0.02 percent on the day. Financials added nearly three-quarters of a percent, whilst industrials were dragged down nearly one-third of a percent.

MTN basically aired all of their dirty laundry and made sure that they shunt the lot through. So, as such, the company is likely to report a wide loss when they deliver their six month numbers today. And rightly so, they must make sure that Mr. Market sees all of the horrible bits. The Nigerian fine will shave off 474 cents per share, forex losses will shave another 135 cents per share, whilst losses by tower companies a roughly equivalent amount. Equally the hyperinflationary environment in Iran and further weakness in their other two core markets, Nigeria and South Africa will impact negatively on earnings. Push the lot through, make the most of what is a horrible situation. After taking a dive at the open yesterday, the stock recovered and added three-quarters of a percent. We will cover these in more detail.

Over the seas and far away, across the second largest ocean on the planet (we do like numbers), stocks closed mixed in New York, New York. Choppy is the word used to describe an oscillating session, time is always against you, you cannot stop it. Or make it go faster, I don't know why you would ever want to though. The Dow Jones Industrial Average may have snapped a losing streak in the session prior, last evening the blue chip index shed all of 2.95 points (that is a whopping 0.02 percent), whilst the broader market S&P 500 gained that percentage amount. The nerds of NASDAQ added 0.13 percent by the close. Facebook had a decent day after a little softness post their results (and a surge too, don't forget that), Apple continues to creep higher. Over the last month Apple is up nearly ten and a half percent. Still, the one year return is nearly minus thirteen percent, not a great outcome for stock holders in recent times. For accumulators of the stock, this is great.


Company corner

Cerner, the information technology healthcare business, released results a couple of sessions ago. The company is in a sweet spot, the more time goes on, the more electronic all healthcare records are likely to be. I think that there is an incredible amount of runway left, anyone who visits their local healthcare professional can attest to this. Equally, a procedure at the hospital amounts in a small forest being cleared, so many forms are needed to be filled in. Equally, in the aftercare environment, the more people involved, the more mistakes. From medicine not administered properly, to the incorrect patient receiving the wrong procedure, technology will help prevent mistakes. At the end of the day, that is the company mission: "to contribute to the systemic improvement of health care delivery and the health of communities."

The name itself comes from the Latin word "to discern". The results themselves - Second Quarter 2016 Results, were Mr. Market showing the company the same good judgement. You almost got the sense that the stock was primed for ordinary. Revenues of 1.216 billion Dollars represented a 8 percent increase on this time last year, earnings per share for the quarter clocked 58 cents and were 12 percent better than the 52 cents recorded this time last year. Bookings (i.e. future orders) jumped 9 percent, the total backlog now has grown to 15 billion Dollars.

Bloomberg pegs this years earnings at 2.36 Dollars (or as near to that as possible). That means after the recent price spike to 66 Dollars, in which the stock rallied around 7 percent post results, the price is probably at the correct valuation, 28 times forward. That does seem a little rich, the stock always trades at a slight premium. That is as a result of the company being in an industry that is expected to continue to show the same kind of growth both in North America and across any new territories that they would expand into, high single digit or low double digit revenue growth. The company guided both the next quarter and full year in about the place that the Street had pencilled in numbers, around 5 billion Dollars at the top end of the range (for the full year) and 2.30 to 2.40 in earnings for the full year, slap bang where Mr. Market and Street had expected.

I suspect that whilst this is a difficult company for most to get a handle on, it certainly is a company that has tremendous growth prospects. From making front end reception payment systems in waiting rooms easier to integrate with health insurance products, to the Smart Room, which makes it easier for patient and care staff to know exactly what is going on at all moments, with the touch of a button and a screen to examine vitals and progress. We all know that medical costs can, not only take you several leaps backwards, it can also cripple families with limited (or even comprehensive) health insurance. A company like Cerner continues to use technology to reduce the costs of pharmacies, doctors and hospitals, who in turn pass that onto patients. And ultimately that means more money for healthcare development and progress.

Their most important business, from a sales point of view, is their ongoing annuity income associated with their services business, and the maintenance thereof. Whilst it is important for the company to fulfil that backlog as soon as possible, the ongoing work is equally important. The company are using cloud based services to make their integration systems a lot more affordable, smaller hospital groups no longer need the big capital outlay in order to own all the moving parts with this type of expensive technology. All you need is a quick internet speed (and redundancy) and staff that can adapt easier.

At the end of the day, you are buying a software solutions provider to the healthcare industry, and as such, this is a pretty niche market. We continue to believe that legacy systems across the globe will be replaced with better cloud based solutions and practical cost saving solutions that will encourage healthcare groups to adopt these types of software. The company has also been the speculation of buyout rumours, specifically from IBM, the current market cap is 24 billion Dollars, the premium would be pretty significant were it to happen, and whilst IBM has the ammo, it may be unpalatable for their shareholders to pay that much. We continue to accumulate the business on weakness, we are happy that the market continues to validate the investment thesis.


Linkfest, lap it up

The heading says it all - 5 Ways Capitalist Chile is Much Better Than Socialist Venezuela. When voters are promised the world, it may transpire in reality for a limited time only, and then the whole lot breaks down. The state cannot do, it can only enable.

This is another step closer to getting real time health data for populations. I can see scientists and data researchers drooling at the prospect of seeing real time data from chosen regions of a city - MIT researchers are sending robots into sewers to monitor city dwellers' waste

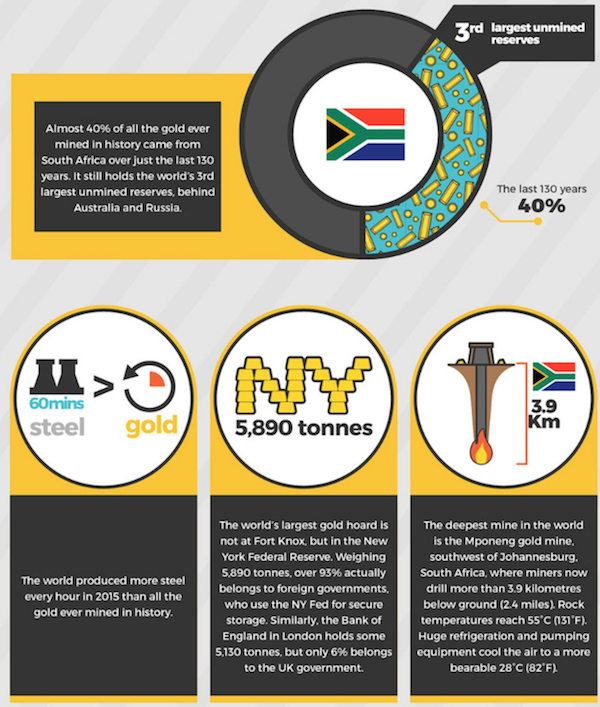
Some interesting facts about Gold. Given its properties of durability, malleability and rareness it makes sense as to why gold was used as a store of value - 31 Incredible Facts About Gold


It is amazing to think that a private company has the resources to land on the moon. Thanks to technology the cost will be around 'only' $25 million - The US government has approved the first private landing on the moon


Home again, home again, jiggety-jog. A company that I like a lot, Priceline, reported good numbers overnight. MTN report today, we still owe you news on Tesla as well as doing Twitter in some detail. Always a whole lot going on, if that wasn't enough for you, there is a small matter of local government elections to keep you busy of course.


Sent to you by Sasha, Byron and Michael on behalf of team Vestact.

Email us

Follow Sasha, Michael, Byron, Bright and Paul on Twitter

078 533 1063
Is the Investment Worth it?

"L'Oreal is a market leader, being the biggest consumer business in their space globally, bigger than Proctor & Gamble by around one-fifth (that division) and over three time the sales of Estee Lauder. Their footprint is pretty breathtaking, nearly 83 thousand employees across 140 countries, selling 32 brands across the portfolio."


To market to market to buy a fat pig Worries about this and that. And now I can see someone who is talking about pattern recognition, my least favourite topic in markets. Showing me a graph of the past, and in some cases all the way back to 1929 and presuming that something is going to happen next is just plain dumb. I can't understand how you can draw a conclusion like that. I suppose it is fear of the unknown, which is often why we don't like to talk about estate planning either, the inevitability of the end is not something we like to deal with in the moment.

OK, that unexciting topic aside, patterns and the ability to see something in the past, that is a great subject for another day. Last evening in New York, New York, stocks ended the session firmer. The blue chip Dow Jones broke their losing streak, closing up around one-quarter of a percent, whilst the broader market S&P 500 ended the session around one-third of a percent better on the day. The nerds of NASDAQ were the best of the majors, adding over four-tenths of a percent, all three indices closing strongly into the bell.

Apple continued to creep higher, the stock was last at these levels two reporting cycles ago, indicating that the collective fears have been allayed at this time. And all the while, believe this, Kim Kardashian (who is famous for being famous, how she got there is none of your kids concern) is looking for a Blackberry and cannot find one. According to Quartz that is. I did however see that tablet sales were trending lower, I guess the device is made so darn well and lasts so long.

Across to our neck of the woods, where local was lekker and standing in line was a slight inconvenience for participating in the fine idea that is inclusive democracy, stocks were closed for the day. Hence nothing from our side, humblest apologies! Stocks were all heading lower, you could take your pick of reasons as to why. Commerzbank and the broader European banking landscape, not well capitalised enough and needing a whole lot more support I am afraid. Weaker data from the US recently, apparently all the PMI numbers were not what Mr. Market wanted. I had seen the CFO of the German institution suggest that you were not to worry, the second biggest bank in the fourth largest economy in the world was going to be ok, and if anything represented an opportunity for less risk tolerant investors. Yes? The bank stock price is down 54 percent over the last 12 months. Tell that to the choir who have been singing another tune there old chap.

And then my personal favourite (not), Japanese stimulus not expected to move the needle. Huh? Japanese stimulus has and hasn't worked, depending what data you cherry pick. Anyhows, the Japanese are rich and highly evolved as a society.

Back on the local front Tuesday, it was, as we said up above, a pretty broad based all fall down session, resources being the only stocks that stuck out with any conviction. And in amongst those, the heavyweight gold stocks led the charge, up strongly. MTN took more pain, the Naira devaluation, whilst welcome in the long term and meeting the "parallel" (i.e. real) market rates is the right thing, the pain in the very short term is not great. The stock continues to take pain on weakness in the local Nigerian currency, and I am afraid that there is very little that one can do, except see where it settles.


Company corner

Cosmetics and the application thereof is thousands of years old. The ancient Greeks, the ancient Egyptians all applied make-up in different forms, as did the Chinese and the Japanese. It is not a new phenomenon. In the recent era, in Europe and the Americas, the rise of make-up can be directly linked to a rise in urbanisation, more urban related activities (eating out, visiting hotels, seeing plays and the opera and the like) gave rise to the fashion industry being more accessible and more sought after for "ordinary people".

People were being seen outside of the fields and forests, and normal upper-middle income people would want to look good. For one another of course, this applies more to modern day society than at any given time. In an era of Instagram and selfies, the need to look better has never been more important. There are multiple reasons that woman wear makeup, including the need to look older or younger, to enhance beauty, to get a clearer complexion, to look attractive, to raise confidence. There can be a multitude of reasons. L'Oreal is not just a cosmetics business, they are huge in the hair business.

L'Oreal is a market leader, being the biggest consumer business in their space globally, bigger than Proctor & Gamble by around one-fifth (that division) and over three time the sales of Estee Lauder. Their footprint is pretty breathtaking, nearly 83 thousand employees across 140 countries, selling 32 brands across the portfolio. They hold over 35 thousand patents, having registered nearly 500 alone last year, and comfortably over 10 thousand over the last decade and a bit. The company runs 44 factories and 153 distribution centres worldwide. It is a big business. The company reported their first half numbers for the current financial year last week, not much fanfare and rah-rah involved, the company is after all French.

A couple of tables, remembering that all of these numbers are in Euros of course. This is for both the second quarter and the first half simultaneously. Herewith the sales and profits:


You can see how incredibly profitable the business is, what is always astounding is that their advertising budget is an amazing 30 percent of total revenues, 29.4 percent to be exact. Byron once described this as spending more on telling you how awesome the product is than on making the product awesome. R&D actually represents 3.2 percent of all sales. I suppose with a lot of competition, you have to make sure that you are under the nose of your customer all of the time. And then per product line, which is the most profitable? You can see by a country mile that the consumer products makes up the bulk of that.


The Body Shop stunk up the joint, as you can see, it swung to a loss there. It is small though. The luxury market from coats to watches, handbags to jewellery and everything in-between (which includes this business) has been under pressure globally. We really like the sector, we think that the stock price is well placed to take advantage of an ever increasing and swelling middle class globally. The stock price in Dollars has underperformed, we expect that it is just a matter of time before the market re-rates the stock. Stay the course, this is the cream of the crop.


Linkfest, lap it up

This world record attempt has been doing the rounds on social media. Im not sure the reward matches the risk level of jumping out an aeroplane, with no parachute and aiming at a net (very small when you are high in the sky) - Skydiver Free Falls 25,000 Feet With No Parachute

Having loyalty cards with preloaded money, is a great way to raise interest free cash. In Starbuck's case the amount they have to work with is rather large (more than the market cap of Famous Brands) - Starbucks Holds More Cash Than Many Banks

Infographic: Starbucks Holds More Cash Than Many Banks | Statista
You will find more statistics at Statista

Imagine if slowing the ageing process or speeding up recovery after an operation meant 'all' you had to do was get a blood transfusion from someone younger than 25 - For $8,000, a clinical trial will inject you with young blood to see if it makes you younger.

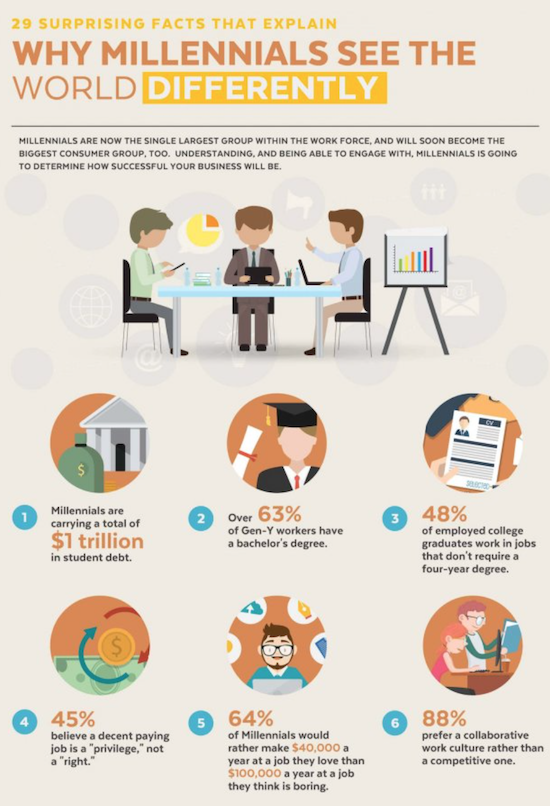
As millennials become the biggest generation globally, knowing their characteristics is important for making investment decisions - 29 Facts That Might Make You See Millennials Differently


Home again, home again, jiggety-jog. Stocks across Asia are higher. Our stock in the office is higher, we all enjoyed our voting experiences yesterday. Some more results overnight, we will get to them all!


Sent to you by Sasha, Byron and Michael on behalf of team Vestact.

Email us

Follow Sasha, Michael, Byron, Bright and Paul on Twitter

078 533 1063
Tuesday, 2 August 2016

What the Heck is Tech?

"Apple is part consumer, part a manufacturer of fine products, part healthcare in the future, part utility. Music, media and the way we consume could turn those more into utilities (like electricity and water). Amazon and Alibaba, are they tech stocks or simply new age retailers?"


To market to market to buy a fat pig I got a message on my phone saying that the oil market was now a bear one. Meaning that from the recent highs, the oil price, or at least NYMEX had fallen by more than twenty percent. And then I had to shake my head at the most ridiculous levels and patterns that humans assimilate with, in order to give them meaning and direction. The truth is that there is not a single human being who can tell you what is going to happen tomorrow, let alone next week or month. The longer it goes, the more likely they are to be wrong when making these predictions.

Prices today are set as a result of the supply and demand fundamentals and the outlook in the foreseeable future, be that the next 18 months or so. The participants (machines too, coded by people) who trade the stock, the bond, the derivative or future or the commodity all take their different views right now. Some may have owned the stock for two minutes, two days, two weeks or two decades, yet may call it quits today, all at the same time. Everyone has their own time horizon and everyone would like to think that they are right. And what I learn every single day is that seemingly every participant in capital markets has their own unique theory on how things are going to pan out. Facebook is this and that as far as earnings are concerned, heck, the valuations may be one thing, the business itself may be completely different by the turn of the next decade.

Ultimately all participants in capital markets have exactly the same goal, not to lose any of their starting capital and to make more money than the last person, so that they can enjoy the spoils. I was talking to my dad the other day about hunters and gatherers in society, the deal makers and the risk takers can be the hunters. The high profile of the mammoth slayers captures the headlines in modern society. CEO x or y or z makes so much, whoa! What you don't see are the late nights, the huge personal sacrifices. The gatherers are more cautious, less leveraged and beaver away, not always winning. There is a lot to be said for both styles, equally investing can be measured against these two styles. In the end, it is all about balance. Not losing any of your starting capital and beating inflation plus your goal consistently.

Technical terms mean little, they take history and tell you what happened. There isn't even a level of recall. Technical analysis sticks lines on a graph and draws other lines. Pattern recognition is great for knowing that you must not eat those berries, they are poisonous, or don't stand directly in front of a charging wooly mammoth (you will lose), it tells you nothing about tomorrow or next week. If you are using a historical graph to tell you what is going to happen next, you might as well go to the mom and pop soothsayer or card reader down the road. They don't know either. Again, there is nothing that I can do about it, people will always look to those that have knowledge. Those who are negative always grab the headlines. I remember someone once said, those that "predicted" the financial crisis were not very good at predicting the subsequent recovery, now were they?

All I can say is that oil prices might have had this very close correlation to market moves around half a year ago, the 20 percent plus fall in oil prices has coincided with stronger equity markets. Normally the comments at the bottom of any news piece are very low on impartiality and very high on the bigot scale. There is one at the bottom of the WSJ article titled U.S. Oil Prices Enter Bear Market that nails it in that style:

    "Lets' see... Low oil prices are good for consumers, particularly poor people. Bad for communist dictatorships, socialist dictatorships and devil worshiping barbarian dictatorships. Whoopee!"


Ha ha, thanks for that Harlin Smith. It does reveal the biases that Harlin has, it was definitely worth the share.

Market temperature time. Stocks across the seas and far away in New York, New York ended mixed again, another losing session for the Dow Jones Industrial Average, both the S&P and Blue Chips were off a smidgen. The nerds of NASDAQ continued to climb higher, Alphabet, Apple, Amazon and even Alibaba all contributed to tech stocks gaining on the day. Although, the lines drawn on what is a tech stock and what is not still escapes me. Search may need hardware and software, it is about information. Information has always existed, it is now just more accessible to humanity day in and day out than at any other point in history. And it will be better tomorrow.

Apple is part consumer, part a manufacturer of fine products, part healthcare in the future, part utility. Music, media and the way we consume could turn those more into utilities (like electricity and water). Amazon and Alibaba, are they tech stocks or simply new age retailers? Very different from one another, these two. Tech is too broad and index boxing requires a big re-think in my book. It is for those who like to call the macro outlook, and then decide which sectors are best. We prefer heading directly for businesses.

There was news related to Elon Musk and two businesses that he is very instrumental in. Two becomes one it seems - the WSJ reports Tesla and SolarCity Agree to $2.6 Billion Deal. I read some of the gumpf in the SEC filing yesterday - Merger Agreement. This is below the original price, that is why the Solarcity share price came under pressure. Tesla probably feels like they need to do this, lowball the offer for shareholders to accept. I get the sense that Solarcity shareholders will accept, regardless.

On the local front stocks rallied nearly two-thirds of a percent, off the highs for the day. The rally was pretty broad based, Nedbank delivered results that crushed it. Of course crushed it if you exclude their Nigerian business, across both retail and business banking, as well as Corporate and Investment banking it looked amazing. Well done to Mike Brown and team. He seems like a regular nice guy, I had the opportunity in passing him in-between interviews at CNBC Africa yesterday. Nedbank was up nearly 7 percent, Sanlam added over five percent, Bidcorp was up nearly 4 and a half percent. At the opposite end of the spectrum were companies like Brait and Mediclinic, Brexit after smells still linger.

This morning there is the announcement from AB InBev and SABMiller, they are looking to complete the transaction by October the tenth. It was actually released last evening - Expected timetable envisages completion of recommended combination. What needs to happen is that both sets of shareholders need to vote on the deal, first things first. That meeting for both sets of shareholders is taking place on the 28th of September. The expectations are for cash and the new combined entity to be available to the sellers (SABMiller) and new buyers of Beer-mega-corp on 10 and 11 October.

Linkfest, lap it up

As populations grow and as the urbanisation trend continues property becomes more scarce, meaning prices in major cities have sky rocketed. A bigger part of peoples living expenses is now going to rent - If they're lucky, British millennials will barely earn more than Generation X in their lifetimes. How long will it be until going into an office daily is a thing of the past? Meaning we don't all need to live close to CBD's

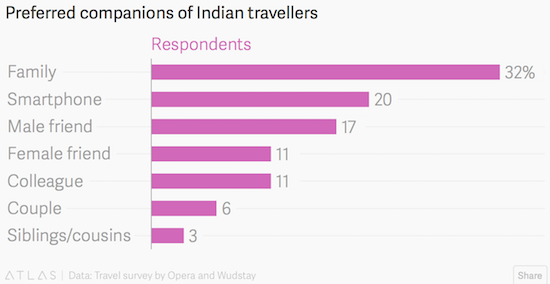
You haven't gone on holiday unless you can put pictures up on social media that you were on holiday - Indian travellers "like" internet access more than a bottle of wine or a hot shower.


Talking of tourism, being a space tourist will soon be something that is possible - Virgin Galactic gets FAA license to start flight-testing its spaceplane

Just wow. Nothing else one can say of this very long read about "The Brazillionaires" - Brazil's Billionaire Problem.

And then on other related matters, Brazil and otherwise, the Olympics are around the corner. There may be multiple concerns, the games will be a success, a roaring success methinks. The satire publication, The Onion has a light hearted look at a map of Rio - Guide to the Rio Olympics. My personal favourite: "125-foot-tall statue of Jesus Christ that can be viewed from every tourist's Facebook album."


Home again, home again, jiggety-jog. I saw some fellow write that he had been blogging for five years, his main reason to start was to clarify his own thoughts and enforce commitment, he says. I thought back to the reasons why I started this daily ritual and why we do it. The same thing, it does a few things, forces commitment to you, your colleagues and most importantly to your clients, without whom you never have a business. We will always remind ourselves that at the core of our business is the client and your ability to deliver long term returns with the correct service levels. It ain't easy, it is why it requires doing the same thing day in and day out.

Many youngsters have this idea that businesses are glamorous places to work. Whilst there can be the pomp and ceremony associated with many client facing businesses, ours aims to deliver superior long term returns with the best possible service levels. You have to do the hard stuff right, and repeat them. We have been at this blog for over 13 years now, since the middle of 2003. The journey continues day in and day out, we enjoy what we do and always appreciate the feedback from the community and our clients. Here is to the next 13 years!

Company news still owed to you. We will get to that, they are not going places (the companies are not moving). You should go places, you should vote tomorrow. Don't forget to do that. Ever.


Sent to you by Sasha, Byron and Michael on behalf of team Vestact.

Email us

Follow Sasha, Michael, Byron, Bright and Paul on Twitter

078 533 1063

Monday, 1 August 2016

Amazing Amgen

"Whether or not you understand what the drugs treat, or whether or not you simply try and understand the specific therapies, that does take a big amount of new reading. Mostly into fields where there could have very little expertise"


To market to market to buy a fat pig On Friday there were more than a few things going on. There are always "things going on", Friday had a disappointing US GDP read, which caused the Dollar to lose value to most of the majors across the globe, including the ZA Rand. Even though politicians were saying the most amazing things over the weekend.

See, the Rand strengthened? Why, oh why, is nobody saying that the brilliant president and the treasury are saying all the right things that foreign investors want to hear? Perhaps it is the fact that politicians have been politicking that they cannot put their foot in their proverbial mouths. Anyhows, we always maintain that it is the lay of the land, the global land, that sets the mood for emerging markets and whether or not the flows are likely to be directed in that direction as a result of the search for yield. That is what we always maintain. So that means it is not us? Nope. As Michael said this morning, when you are small, you are small.

After a tumultuous week of shareholders saying this and that, and AB InBev upping their pound price of SABMiller, the board of that fine institution recommended the offer to their shareholders. See the Bloomberg story - SABMiller Board Recommends AB InBev's New $104 Billion Offer. What I find quite laughable and in almost all of these situations, the board always reckons that the deal hopelessly undervalues the true potential of the company, or almost always should be a whole lot more. Grossly undervalued, blah-blah-blah. The share price of SABMiller was trading below 30 Pounds a share before the deal. And even then the stock looked expensive, right now the stock trades on a 35 multiple.

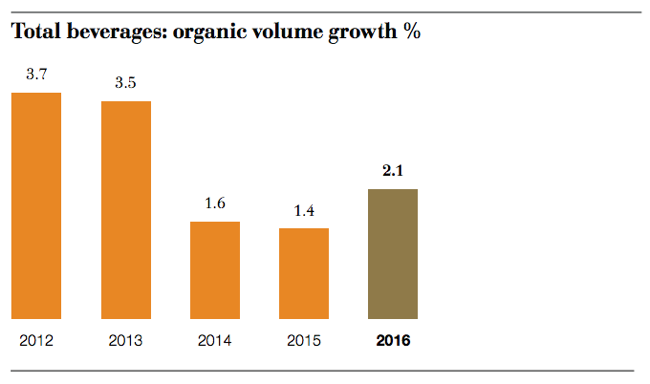
I am happy to buy a business that has top line growth in the high teens on that sort of multiple, here are two graphs from their last annual report. The first one is the growth in volumes. Now, granted, there is only so much beer that customers can consume more of on a year to year basis. In many of these markets the base is still for most intents and purposes quite low, relative to some of the developed world. Here goes, from the last annual report:


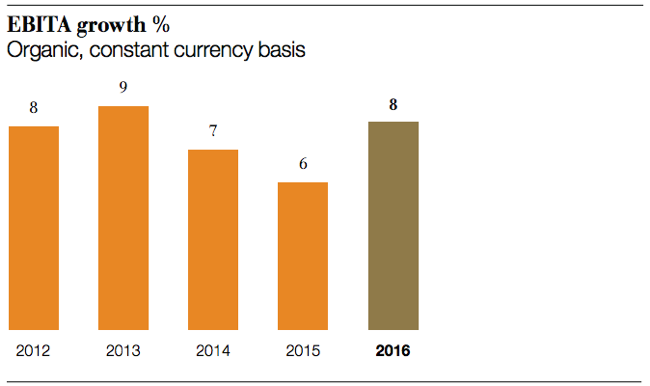
And then more importantly for investors, what about profits? In the high single digits mostly.


AB InBev are after the two-thirds of the business that is Latin America and Africa. Lager volumes are growing (or grew in 2015) at 6 percent in Latin America, with soft drinks at 4 percent. Across our continent, as per the last annual report, larger volumes grew at 5 percent, with soft drinks at a more impressive 8 percent. Here goes:


No Europe, no Asia, (it would seem) focus on emerging markets and be ruthless on costs. That has always been the style of the controlling shareholders of 3G Capital. They will be ruthless by stealth. They will save costs and make the business meaner. Even before you didn't even know it was there. Either way, this now needs to be put to a vote. And that will come soonest, possibly it cannot come sooner for all concerned.

Quick scoreboard check, locally the market fell away through the session, in part due to a stronger Rand. We lost just over nine-tenths of a percent to close well below 53 thousand points again. Over the seas and far away in New York, New York, stocks closed mixed again, the Dow Jones Industrial Average lost 0.13 percent, whilst the broader market S&P 500 and the nerds of NASDAQ gained about the same amount (as the Dow lost). Big week, all about results. Let us get into it below.


Company corner

Amgen reported numbers last week - Second Quarter 2016 Financial Results. It is not as tough to report on a company that has a very focused consumer front facing business, in many cases we use loads of consumer products like Apple (your phone or computer), Google search (or Android phones), Facebook (Instagram and WhatsApp), Amazon (reading your Kindle, ordering online), Nike (go for a run or to gym), JNJ and L'Oreal (shampoos and consumer products), Netflix even, perhaps even Priceline (Booking.com). Whilst you are wearing your Luxottica (sunglasses) products. Those businesses you know and use, and you are very familiar with.

Somehow, a company that makes very specific therapies that in some cases only have a target for 3 to 4 hundred thousand potential customers, that is harder to get a handle on. In fact, as the therapies are definitely for life threatening illnesses, you pretty much hope that you are not ever a consumer of their product. It may well be easier to be a user of Stryker, to get a new artificial hip or knee than to use the therapies that Amgen manufactures and distributes.

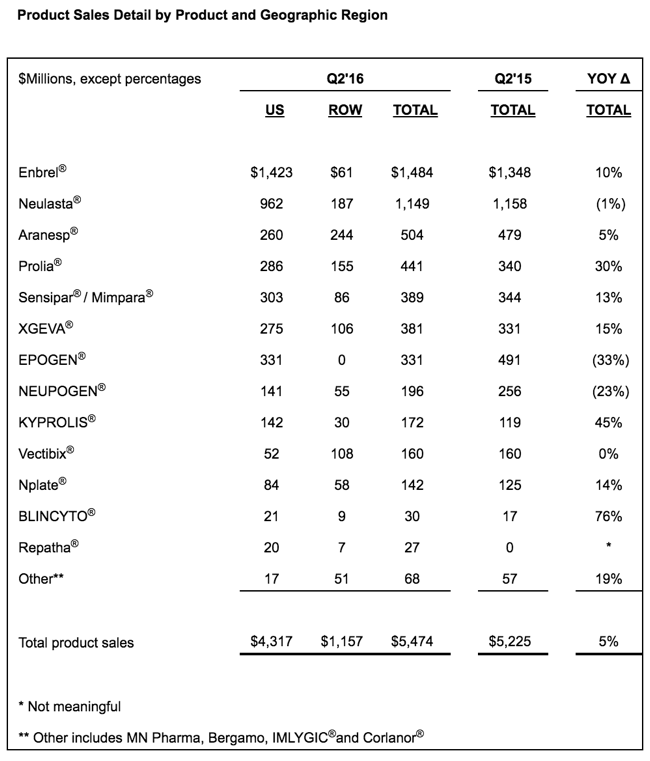
Amgen top sellers include ENBREL, which treats 5 different ailments from Rheumatoid Arthritis to Plaque psoriasis. KYPROLIS treats patients with relapsed or refractory multiple myeloma, who have been treated before. XGEVA prevents serious bone problems. PROLIA helps woman with postmenopausal osteoporosis, specifically with high risk to fractures, to specifically strengthen bones. First, a table of their big hits by sales for the quarter just passed.


Whether or not you understand what the drugs treat, or whether or not you simply try and understand the specific therapies, that does take a big amount of new reading. Mostly into fields where there could have very little expertise. It is funny how we can understand the combustion engine, yet understanding ones own body would take a lifetime. Perhaps we can see the combustion engine, all you need do is to open the bonnet (hood) and peek in. In the same way that you look at an x-ray, you look under at the engine. You really have little idea as to what is going on. Plus, I bet you didn't know that this company (Amgen) has a market capitalisation of 25 percent more than what AB InBev want to pay for SABMiller. I suppose it is easier to drink beer.

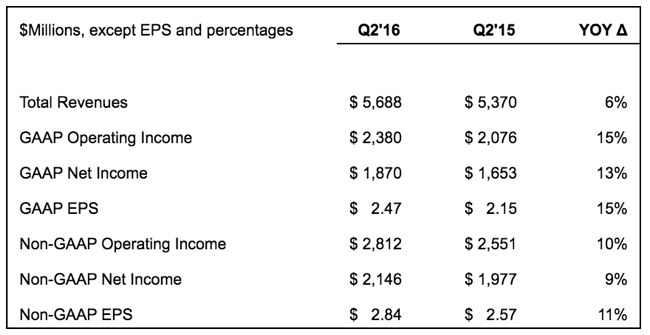
That aside, here is a breakdown of the sales and profit numbers in the associated table with the earnings release:


The company guided higher for the full year, revenues around one percent higher for the full year at the top end of the range, non-GAAP EPS range was pushed higher to a 11.10 to 11.40 Dollars a share range, that is around two percent higher than the prior top end of the range. This is obviously good news for investors. The stock has responded accordingly, over the last month the share price is up nearly 15 percent, in anticipation of good numbers. On a historical basis the stock still looks decent value at 18.2x earnings, forward (i.e. this year), that unwinds to less than 15 times. And to the end of next year, the analyst community has it at around 13 and a half times. Which, as you can see the earnings growth rate, is quite something that it is that cheap! Plus, post tax there is a two percent dividend to boot.

This is not your typical biotech business, they are a lot more mature. You may recall when we introduced the stock as a core recommendation last year in October - Amgen (2015) Q3 numbers we pointed out that they were halfway through their 4th decade of business. I will copy and paste what I wrote back then today, I strongly believe it: I would rather own a company and part with my money to own a piece of a business that is trying to cure humanity. The therapies may be wildly expensive, there may be an ethical argument about the cost of the treatments, without that, the company would not be able to recoup the money spent engaging in finding these cures.

All things being equal, the stock price should continue to gain traction as some strong pipeline therapies add to their already growing business. Finding cures and therapies for breast cancer, inflammatory diseases, migraines, that is what is in the pipeline currently and close to approval. We recommend this company as a strong buy.


Linkfest, lap it up

Some user numbers from last weeks Facebook results, the user base is growing as well as the number of people using the platform daily, instead of a couple times a month - Facebook Users Show No Signs of Tiring. As the number of users starts to get saturated, the growth comes from the amount of time that people spend on the platform. More time per day means more eyeballs for advertisers to pay for.

Infographic: Facebook Users Show No Signs of Tiring  | Statista
You will find more statistics at Statista

This graph probably shows you the reason why people voted for Brexit. People in the UK are earning less today than 8 years ago, so they want change - UK & Greece Come Bottom For Wage Growth

Infographic: UK & Greece Come Bottom For Wage Growth | Statista
You will find more statistics at Statista

Reading about Jupiter reminds me just how small we are on Earth. I am also amazed by how much there is still to learn about our solar system - Jupiter's Red Spot Churns Out Air Hotter Than Lava.

If you don't know the story of Khizr Khan, his wife and family (and personal sacrifices), where have you been? I urge you to try and watch the speech if you haven't (Khizr Khan's powerful DNC speech (Full speech)). The upshot of the speech is that not only did it inspire many, it also caused the U.S. Constitution to become Amazon's best-seller after father's powerful rebuke of Trump.


Home again, home again, jiggety-jog. It is another big week for stocks, reporting all week long to give a clearer picture of what we are likely to expect. Equally, there is a jobs number at the end of the week. I wonder what and how the Brexit thing would have influenced US corporates to hire (or mostly not hire). We still have L'Oreal and Twitter to cover from the numbers from last week. And then of course voting day, that is likely to be fun as always.


Sent to you by Sasha, Byron and Michael on behalf of team Vestact.

Email us

Follow Sasha, Michael, Byron, Bright and Paul on Twitter

078 533 1063